Buyers who stretch to win competitive bids on distressed properties often discover that banks will not renegotiate once a highest-and-best offer has been accepted. As a result, the deals collapse before closing.
Bank-owned homes, known as REO properties, often draw multiple competing offers because lenders price them to sell quickly. That bidding pressure can push buyers past their true budget, creating problems that don’t surface until after the contract is already signed.
The Competitive Bidding Trap
In Chicago’s bank-owned property market, multiple-offer situations are common. But according to Tamika Marks, owner and managing broker at Trademarks & Associates, LLC, the competitive pressure that drives buyers to submit aggressive offers is also a leading reason those deals fall apart before closing.
Marks has worked corporate-owned and distressed assets in Chicago for 23 years. She says the pattern repeats: a property generates strong interest, buyers escalate their offers to win, and then, once under contract, reality sets in.
“Oftentimes people feel as though they may have overbid because it’s usually a multiple-offer situation,” Marks says. “In most cases, the seller does not make repairs. The homes are as you see them.”
In a standard residential transaction, a buyer who discovers unexpected issues during inspection can renegotiate. In the REO, or real estate owned, market, that leverage largely disappears. The property is sold as-is, and the bank’s price position is firm, especially when the accepted offer came in above asking.
Why Banks Refuse Reductions
When a bank-owned property receives multiple offers, the listing agent calls for highest and best, asking every interested buyer to submit their strongest offer. The bank then selects from that pool.
Marks says that once a buyer has declared their highest and best and the bank has accepted, the logic of renegotiation collapses from the seller’s perspective.
“Asking for a price reduction after you’ve overbid is a little bit of a difficult task to get the bank to say, okay, you offered $20,000 more than what we’re asking, now you want to reduce that price,” Marks says.
The bank knows other buyers were willing to pay at or near the accepted price. The buyer voluntarily overbid and had the chance to assess the property before submitting an offer. Granting a reduction under those conditions is a concession the bank has little reason to make. The result: the buyer wants relief, the bank will not provide it, and the deal collapses.
Financing and Repair Gaps
Overbidding is not the only cause of contract failures. Marks identifies two additional patterns: financing miscommunication and underestimation of what it takes to make a distressed property livable.
“A buyer may have underestimated the process or what it takes to make the home habitable,” Marks says. “Usually they fall apart because they have a lack of communication when it comes to their financing or their lending partner.”
These failure modes often intersect. A buyer who overbids may also be stretching the limits of their financing, leaving little room for repair costs after closing. When a lender raises concerns or the numbers no longer work, the deal structure can fall apart quickly.
The Naperville property Marks described illustrates the full cycle. The listing drew 26 offers across two market activations. The first buyer went under contract, then attempted to negotiate a price reduction. The seller rejected the request. That buyer exited. Marks returned to the remaining offer pool and found a second buyer willing to proceed on the original terms. The deal closed, but only after the first contract failure added weeks of delay.
Matching Buyers to Properties
Most distressed properties suit investors or buyers comfortable managing significant repairs. Owner-occupant buyers typically need financing that requires the home to be move-in ready, a standard most bank-owned inventory does not meet.
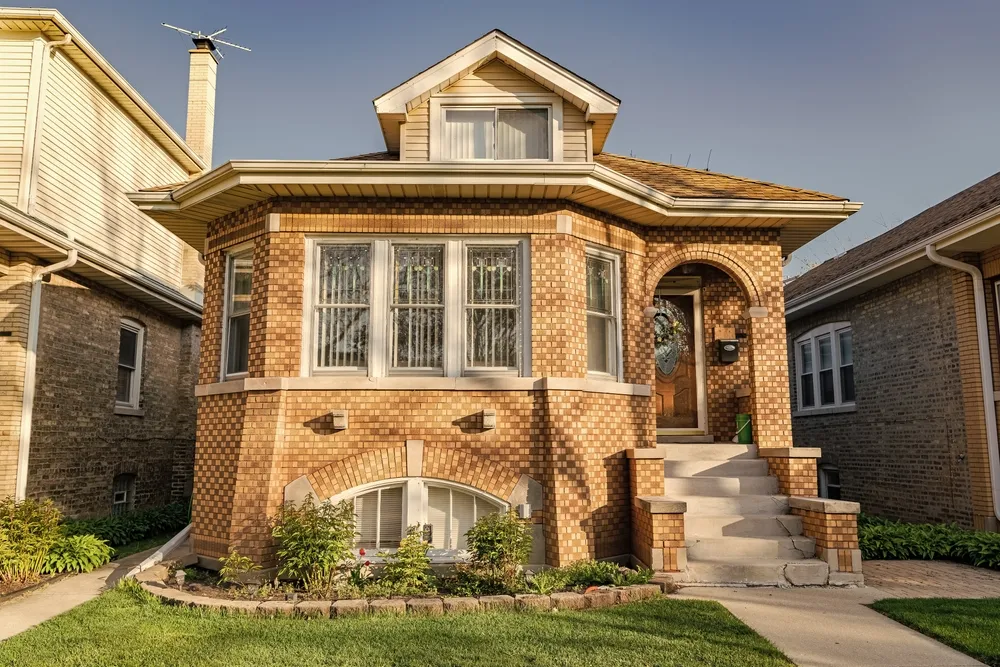
“Even though they’re popular in very, very favorable neighborhoods, they’re just not in the condition where an owner-occupant can come in and sit their suitcase down and say, honey, I’m home,” Marks says. “You have to put some work into them.”
That mismatch between buyer expectations and property condition is another reason contracts fall through. Owner-occupant buyers drawn in by a competitive price often realize, after going under contract, that the scope of work exceeds what they can finance or manage.
Preparing Before the Bid
Marks says the key to closing a distressed deal is preparation before the offer goes in, not negotiation after.
“Once you determine that this is your highest and best offer, you have to be ready to stand by it,” Marks says.
For buyers, that means walking the property carefully, consulting with contractors, and testing their financing against realistic repair costs before committing to a number. Each failed contract costs the seller time and delays getting a vacant, distressed property back into use. In Chicago neighborhoods where multiple-offer bidding remains common, buyers who understand the as-is terms of an REO deal before they bid are the ones most likely to close.
About the Expert: Tamika Marks is owner and managing broker at Trademarks & Associates in Chicago, focused on corporate-owned asset disposition—REO sales, reverse mortgage liquidations, and bank-owned properties across the city’s South Side and surrounding suburbs —for 23 years.
This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.