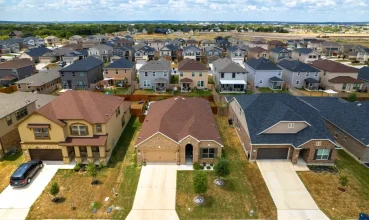
The Opportunity Zone program was designed to channel investment into operating businesses, tech startups, healthcare companies, service firms that could locate anywhere, including underinvested communities. Instead, more than 95% of the capital has flowed into real estate development. That imbalance is now a defining feature of the program, and the recently enacted 2.0 legislation is reinforcing it.
Gerry Reihsen, a corporate securities attorney at Reihsen & Associates who has spent more than four decades in capital formation and real estate fund structuring, sees a straightforward explanation. “Real estate development is very financial model oriented, and the likelihood of gains at the end of a 10-year hold is fairly high,” he says. “So you know that the time and effort you put into setting up Opportunity Zone arrangements is going to pay off.”
Operating businesses outside real estate, Reihsen says, are too focused on day-to-day survival to engage with a tax benefit that requires long-term structural planning.
What Actually Changed Under 2.0
The updated statute alters the program’s economics in several concrete ways. Under the original rules, all investors had their capital gains taxes deferred until December 31, 2026 – a fixed, shared deadline. Under the new rules, each taxpayer gets an individual five-year deferral tied to when they invest in a qualified opportunity fund.
The reduction in taxes on invested capital gains has also changed. The original program offered a potential 10 to 15% reduction. The new version standardizes a 10% reduction after the five-year deferral, with a significant rural carve-out: investors in rural qualified opportunity funds receive a 30% reduction in their invested capital gains, along with lower thresholds for what constitutes a qualifying property improvement.
The core benefit – tax-free exits on gains after a 10-year hold – remains intact.
A Regulatory Gap in the Transition
The most consequential issue right now is not in the statute itself but in how the IRS is interpreting the transition between versions. The original legislation provides that OZ 1.0 designated zones continue through the end of 2028. But the IRS has issued a concept notice – not yet proposed rules – that effectively makes it impossible to begin a new project in an OZ 1.0 zone after the end of 2026, two years ahead of the statutory deadline.
The threshold the IRS outlined requires investors wanting to use OZ 1.0 zones to have a business plan, financial model, and projections in place before year-end 2026, to have raised debt or equity equal to 10% of the project budget, and to have spent or committed to spending at least 5% of that budget by the same deadline.
“I don’t think the IRS has the regulatory authority to have done that given the statutory situation,” Reihsen says. Congress considered a bill to cut the old zones’ timeline to the end of 2026 and rejected it – evidence, in Reihsen’s view, that legislative intent was to preserve the 2028 date. He estimates there is roughly a 50-50 chance the rule will be revised under industry and governmental pushback, noting that governors and other agencies have weighed in alongside practitioners.
For now, the concept notice is driving urgency. “We’re helping a lot of people set up that way because they have OZ 1.0 zones that they want to invest in, and so they’re scrambling,” he says.
Why Conversions Are the Preferred Structure
The OZ statute essentially requires that capital go toward new construction, substantial improvement of existing assets, or acquisition of properties not yet placed into service. Investors cannot simply buy a stabilized apartment building or office property in a designated zone.
Hotel-to-multifamily conversions have emerged as a particularly efficient structure. Reihsen describes a recent client engagement involving a former Holiday Inn near the site of the old Stapleton Airport in Denver – an 11- or 12-story property in an Opportunity Zone. The advantage of buying an operating hotel is that investors receive immediate depreciation benefits while the asset still generates revenue. Floors can continue operating as hotel rooms while others are converted to apartments, producing tax benefits from day one rather than waiting until a ground-up project is placed into service. “It really juices the IRR,” Reihsen says.
The Case for a Personal Qualified Opportunity Fund
One of the less widely understood applications of the program is the personal, self-directed qualified opportunity fund. Reihsen describes it as functioning like “a Roth IRA on steroids.” A high-net-worth taxpayer or family office sets up its own QOF, invests capital gains into it, and after the 10-year mark can buy and sell assets tax-free for up to 20 additional years.
Reihsen contrasts this with the 1031 exchange, which he says is “often called swap till you drop” – an investor exchanges one property for another indefinitely, deferring taxes but never realizing the benefit personally, instead passing it to heirs. With a personal QOF, the tax-free benefit accrues to the investor during their lifetime.
During the deferral period, Reihsen says, a well-structured personal QOF can generate losses that offset the deferred gain obligation, potentially reducing the eventual tax bill substantially.
Where Deals Break Down
Two issues consistently trip up investors. The first is timing: a taxpayer who directly sells an asset has 180 days to get capital into a qualified opportunity fund. Partnership owners get additional windows – 180 days from December 31 of the gain year, or 180 days from March 15 – but must choose one. The second is property qualification: investors frequently approach with existing stabilized properties in Opportunity Zones that do not qualify under the statute’s improvement requirements.
Reihsen says the most common source of problems is using advisors who lack specialization. “The big mess-ups are usually when people use advisors who aren’t specialized,” he says. He recommends that investors bring in both an attorney and a CPA with dedicated OZ expertise, even if they already have trusted general practitioners.
About the Expert: Gerry Reihsen is a corporate securities attorney at Reihsen & Associates, with more than four decades of experience in capital formation and real estate fund structuring, specializing in Opportunity Zone investments.
This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.