The gap between what entry-level buyers in Maine can afford and what the housing stock actually offers is not a matter of timing or interest rates. It is a supply problem with no clear solution on the horizon, and it is reshaping how families in the state approach homeownership altogether, according to Josh Cousineau, who leads a residential team at Cousineau Real Estate covering a stretch of Maine from north of Bangor down to Kennebunk.
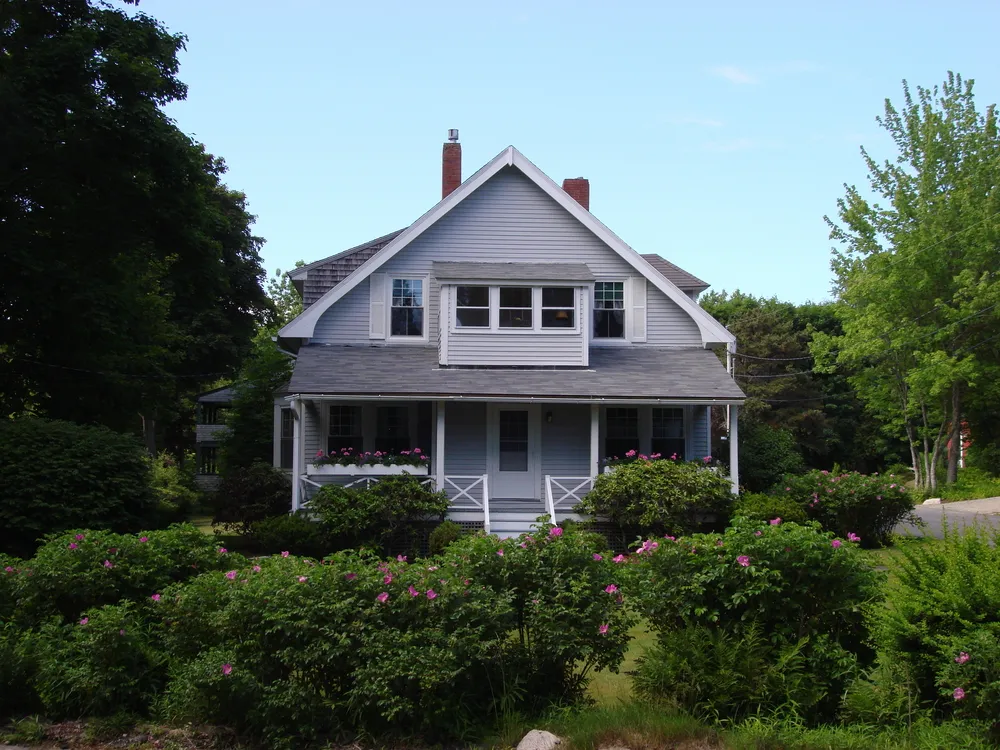
His team has five or six active buyers right now approved for under $230,000. These buyers are seeing very few properties, sometimes waiting 2-3 weeks before something that will work for their loan comes on the market. “That house doesn’t exist,” he says of the move-in-ready home in that range that can also qualify for government-backed financing like FHA or USDA loans.
The result is a market that functions in two distinct tiers. Between $350,000 and $600,000, inventory is adequate; second-time buyers and upgraders have options. Below $250,000, the market is functionally frozen.
When the Market Can’t Serve Its Buyers, Families Step In
The gap is not being filled by new construction or creative lending. It is being filled by family money. Cousineau describes clients buying land to build homes for their adult children because the existing market offers nothing they can afford. “It’s not feasible for them to buy houses and we want to help them out,” he says.
Generational wealth transfers and family compounds are becoming workarounds in a market where building affordable homes is cost-prohibitive. Insulation standards, heating requirements, and general construction costs in the Northeast have pushed the floor price of new builds well above what entry-level buyers can finance. Mobile homes on land – a traditional alternative – often fail to meet lending requirements because they have been moved multiple times or do not comply with current standards.
“If someone could figure out how to build a home in that price point that could pass government lending, they could sell a lot of them,” Cousineau says.
Property Taxes Are Redrawing the Map
Affordability is not just about purchase price. Property tax variation between neighboring towns is large enough to shift buyer behavior across municipal lines. Cousineau describes buyers who loved a home in one town but chose a more expensive house in the next town over because the lower tax rate made the monthly mortgage payment smaller. The difference between a $2,100 annual tax bill and a $5,500 one translates to roughly $200 a month, enough to change what a buyer can afford.
“I had a buyer yesterday,” he says. “They said, ‘We want to be in this area but not this town because the taxes are just too high.'” The migration pattern runs in one direction: away from Portland, which is growing more expensive, toward Lewiston, Auburn, and points north and west where prices drop. That movement then cascades, pushing Lewiston-Auburn buyers further north in turn.
Cousineau says many municipalities do not seem to be thinking about the long-term consequences. Towns with high property tax rates are effectively removing themselves from buyer search lists altogether.
Move-In Ready Sells Fast. Everything Else Waits.
Seasonality compounds the divide between property types. In a New England market heading into fall, buyers are not taking on large renovation projects with winter approaching. Move-in-ready homes in populated areas are going under contract within two to three weeks. A small three-bedroom listing in Portland drew seven people to its first open house and had offers within two days.
Specialized properties – Cousineau cites a horse farm and a property with a sawmill currently listed – are on a different timeline entirely. Overall days on market have drifted up to 30, 40, or 50 days, a significant change from the pandemic period when properties routinely drew multiple offers within days of listing.
The shift has also changed how negotiations play out. Seller concessions, contributions toward closing costs, and rate buy-downs are now more common than not. Inspection contingencies, which were routinely waived during the pandemic, are nearly universal again. “I have not seen a house that is getting waived inspections for a while,” Cousineau says.
The Backup Offer as a Buyer Strategy
One tactical response to the current market: Cousineau’s team actively pursues backup-offer positions on properties already under contract. Buyers face no cost or obligation, remain free to pursue other homes, and occasionally benefit when the primary deal falls through. About 30% of the backup offers his team places end up closing, according to Cousineau.
The strategy also gives sellers leverage during inspection negotiations with the first buyer. Sellers who know they have a backup offer can hold firmer on repair requests. Cousineau says buyers who take backup positions sometimes secure favorable terms because sellers do not expect the first deal to fall apart and will accept a lower price from the backup buyer rather than relist.
Where Deals Fall Apart
When deals do collapse, Cousineau says the cause is usually agent inexperience rather than financing problems. Experienced agents who understand negotiation and client communication get deals to closing. Deals handled by inexperienced or part-time agents fall apart over minor issues, not because the problems are large, but because the agents lack the skill to negotiate solutions.
He cites a current example: a buyer requested repairs with quotes totaling roughly $5,500 to $5,800. His seller client agreed to handle some of the work and contribute up to $4,000 toward closing costs. The buyer’s agent – an experienced one – framed the response constructively rather than as a shortfall, and the deal held together. “That easily could have gone the other way,” Cousineau says, because a less skilled agent might have presented the same numbers as a rejection rather than a near-complete resolution.
A Seasonal Window With a Structural Backdrop
Looking ahead, Cousineau sees a narrow seasonal window between now and roughly Thanksgiving, after which Maine’s market typically slows through January. His focus is on identifying properties that have sat too long, where sellers are increasingly motivated by the prospect of carrying a home through winter. Longer term, he is exploring conversations with developers about how to serve the sub-$250,000 market, “whether it’s a mobile on land or a small modular or something in between.”
For buyers in that entry-level range, the options remain limited to waiting for the rare qualifying property, relying on family support, or looking further north and west where prices drop but commutes and amenities change. None of those choices resolve the underlying shortage; they only redistribute the pressure.
About the Expert: Josh Cousineau leads a residential team at Cousineau Real Estate, covering Maine from north of Bangor down to Kennebunk.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.