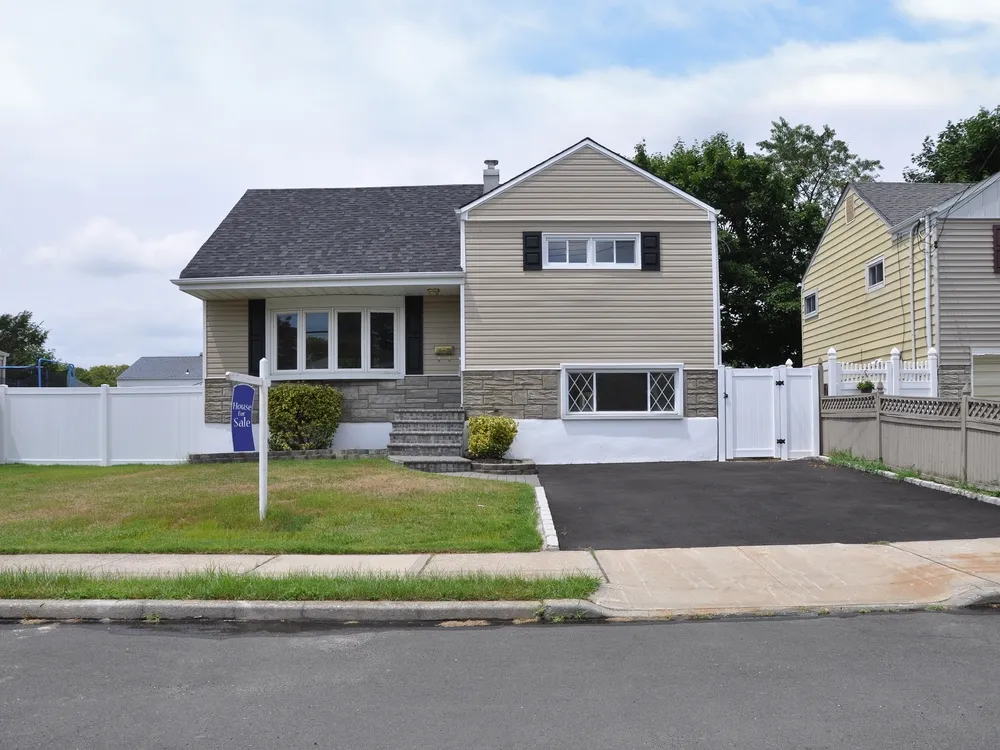
Housing inventory across much of the country has climbed to levels not seen in four years. For buyers, that looks like relief after years of bidding wars and razor-thin selection. But the supply gain is a side effect of suppressed demand, not a surge in new listings, and if mortgage rates decline enough to bring sidelined buyers back, the window could close faster than the market expects.
Christy Bunce of New American Funding, a privately held mortgage bank with over 300 branches and roughly 5,400 employees, sees both sides of this dynamic through the company’s nationwide loan officer network. More homes are available, but fewer buyers can actually qualify to purchase them.
“Inventory is pretty high in a lot of markets, higher than we’ve seen in four years,” Bunce says. For buyers who can qualify, that means more choices, less competition, and more negotiating leverage than they have had in recent memory. Bidding wars have cooled in many metro areas, and sellers are sitting longer.
The reason inventory has risen, however, is not that homeowners suddenly decided to sell in large numbers. Elevated mortgage rates have frozen many would-be buyers out of the market. Demand has pulled back, and homes are sitting. The supply gain is really a demand pullback in disguise.
Bunce believes that “the minute the rates do go down, and they will eventually go down, all that inventory is going to be gobbled up overnight.” The sidelined buyers have not disappeared. They are waiting. When rates decline enough to bring them back, competition for available homes could intensify rapidly, pushing prices higher and eliminating the negotiating leverage buyers currently hold.
Why Qualifying Is Harder Than It Looks
The affordability equation facing today’s buyers is more complex than in previous cycles. Bunce describes it as more than a rate problem: buyers now face high insurance costs and elevated consumer debt at the same time as high mortgage rates. She says many potential buyers simply cannot qualify.
“It used to be just a rate equation,” Bunce says. “But now there are so many other moving parts because insurance is so expensive and people have a lot of debt now because of the environment that we’ve been in for so long now, four or five years.”
That combination means the pool of buyers who can actually act on today’s favorable inventory conditions is smaller than the headline numbers suggest. The buyers who do clear the qualification bar are operating with real advantages, more selection, less competition, and sellers who may negotiate on price or concessions. Those advantages exist precisely because high rates have thinned the competition, which is why they are unlikely to survive a rate decline.
What Sellers Are Facing
Sellers are already feeling the demand pullback. Homes that would have drawn multiple offers two years ago now sit for weeks. Price reductions are more common. Buyers have leverage they have not had in years.
That creates a genuine tension for anyone considering listing. Waiting for rates to drop and demand to return sounds appealing, but Bunce’s view suggests the return of demand may not be gradual. A rapid compression of inventory could push prices higher quickly, rewarding sellers who listed into stronger competition, but only if rates actually decline.
On that front, Bunce is direct: “I don’t think we’re going to get any help from the market anytime soon.” The elevated-rate environment could persist well into 2027, and sellers banking on a quick rebound may find themselves carrying costs longer than expected.
The Trade-Off Worth Weighing
New American Funding’s strategy with its current borrowers reflects the tension Bunce describes. The company is focused on finding loan programs that help buyers purchase now, while inventory is available, rather than waiting for a rate environment that may not arrive soon, and that, when it does arrive, will bring back the competition that has kept buyers shut out for years.
A home purchased at today’s rates carries a higher monthly payment than the same home would at lower rates, and the assumption that refinancing will be available on a convenient timeline carries its own risk. But the trade-off between today’s inventory advantage and tomorrow’s likely competition is real. Buyers who can qualify now face a market that is, by recent standards, unusually accommodating, and that accommodation is a direct product of conditions that will not last indefinitely.
About the Expert: Christy Bunce is President of New American Funding, a privately held mortgage bank.
This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.