The median age of a first-time homebuyer just hit 40, according to Larry Naselli, a residential real estate agent with Baird & Warner in Crystal Lake, Illinois. That figure reflects more than high prices and elevated interest rates. It also reflects a generation reaching financial adulthood later. Many start careers later, build savings later, and reach the housing market with less cash than previous generations had at the same stage. In Chicago’s far northwest suburbs, Naselli says this affordability squeeze has produced a workaround that is changing how first-time buyers compete. Family members are stepping in as private lenders.
Naselli says a notable number of first-time buyers in their twenties and thirties are showing up as apparent cash buyers. Some offer $300,000 to $400,000 with no mortgage contingency. In most cases, the money is not theirs. “They’re not really cash buyers,” Naselli says. “They are to the seller, but they’re really parents or grandparents acting as the bank.”
How Family Lending Works
The structure varies by family, but the pattern Naselli describes is consistent. A parent or grandparent draws on retirement savings or other liquid assets to fund the purchase outright. The home then closes as a cash deal. That gives the buyer a significant edge in a market with frequent multiple-offer situations.
The first-time buyer repays the family member over an agreed period, such as three, five, or seven years. Repayment continues until the buyer can refinance into a conventional mortgage. In some cases, Naselli notes, parents give the money with no expectation of repayment. Private lending within the family is more common.
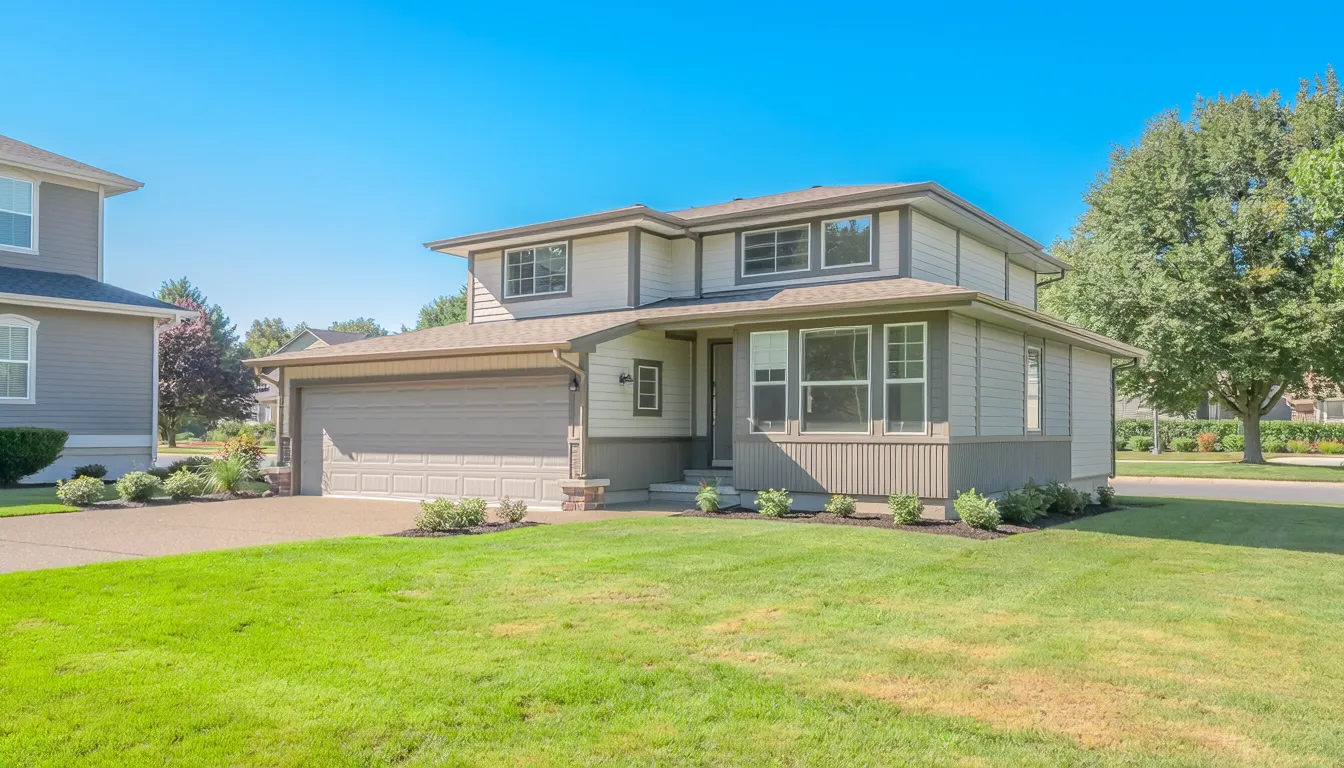
Move-in ready homes priced below key thresholds draw intense competition. In that market, showing up with cash can decide who wins a bidding war. A cash offer eliminates mortgage contingencies, shortens closing timelines, and signals certainty to a seller weighing multiple bids.
Why Cash Offers Win
Conditions in the far northwest suburbs are driving this trend. Inventory across communities like Crystal Lake, Elgin, and McHenry remains below two months of supply, according to Naselli. He says prices are rising 2 to 8 percent year over year, depending on the town. About 25 percent of listings are move-in ready, well priced, and show well. Those homes draw multiple offers and sell at or above list price.
The remaining 75 percent are in mediocre condition or not fully updated. These homes sit longer on the market, take price cuts, and give buyers more leverage. Naselli says 80 percent or more of millennial buyers skip those listings entirely. Instead, they compete for the smaller share that shows well. The result is a two-track market. The best homes draw fierce competition, while the rest sell slowly and often disappoint sellers.
First-time buyers with a conventional mortgage and limited savings struggle to win those competitive listings. A cash offer backed by family money avoids that problem.
Where Assistance Falls Short
In March, the Illinois Housing Development Authority (IHDA) launched a new down payment assistance option for first-time buyers. It offers up to $15,000 and requires only 1 percent down. Buyers repay the assistance when they pay off the loan or sell the home. Naselli considers the program well targeted. It gives buyers cash for more than a down payment. They can also use it for competitive leverage, such as covering an appraisal shortfall when bidding above asking price.
Still, $15,000 only goes so far against competing cash offers of $300,000 or more. Families who turn to private lending are often the ones these programs cannot fully help. Their buyers compete in price ranges where cash offers dominate most.
Naselli says elevated interest rates have not significantly reduced buyer demand in the area. Some buyers on the margin lose purchasing power or no longer qualify for preapproval. Across the broader market, however, plenty of demand still chases a small number of homes. That steady pressure keeps family-funded strategies valuable. As long as inventory stays low and competition stays intense, first-time buyers with family money hold a clear advantage over those without it.
About the Expert: Larry Naselli is a residential agent with Baird & Warner in Crystal Lake, Illinois, covering the far northwest suburbs of Chicago.
This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.