A Million Dollars May Not Buy a Move-In-Ready Home in East Hollywood, Florida


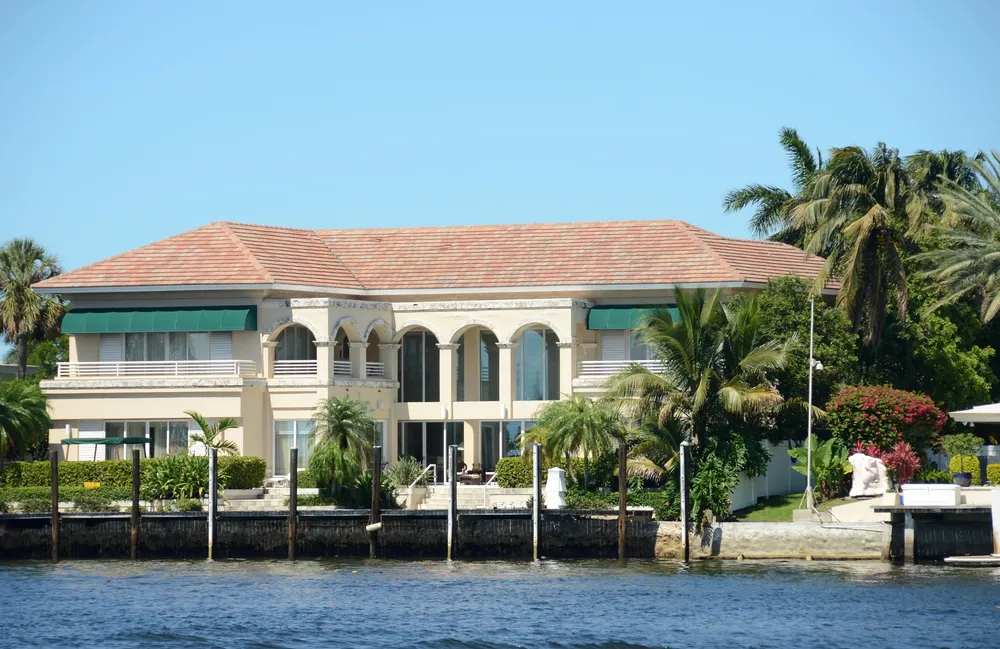
Buyers relocating to southeast Florida’s beachside neighborhoods often assume that spending seven figures guarantees a polished, updated home. In East Hollywood and surrounding areas of Broward County, that assumption leads to serious budget miscalculations. The gap between purchase price and true move-in cost is one of the biggest surprises facing out-of-state buyers.
Lilli Schipper, a Broker Associate at LoKation Real Estate with 22 years of experience in Hollywood, Dania Beach, and Fort Lauderdale, sees this pattern repeatedly in mid-2026. Many of the homes closest to the beach are desirable for their location but decades old. They’re often priced as though location alone justifies the cost.
“Even at a million plus some of these houses, especially in East Hollywood, you still might be buying a house that still needs the roof and plumbing and windows all to be redone,” Schipper says.
Location Over Condition
Hollywood’s beachside neighborhoods developed largely in the mid-twentieth century, and the housing stock reflects that era. Homes sit on attractive lots, often with water access or short walks to the sand. But roofs, plumbing, windows, and electrical systems often have not been modernized.
Sellers price these homes based on location and lot characteristics, including proximity to the ocean, walkability to downtown Hollywood, and access to marinas. Buyers from markets like New York or California, where a million-dollar home in a desirable zip code typically means recent updates, arrive with different expectations.
Schipper notes that these older beachside homes “are wonderful, but they’re older and need work, whether it’s roofs, plumbing, or similar systems.” The charm is real. So is the deferred maintenance behind it.
Hidden Renovation Costs
This mismatch becomes especially painful when layered onto Broward County’s other ownership costs. Property taxes, windstorm insurance, and flood insurance already push monthly carrying costs well above what the mortgage payment alone suggests. Adding a substantial renovation budget on top of a seven-figure purchase price can push a buyer’s total investment far past what they planned.
The risk is greatest for buyers who stretch to their maximum pre-approval amount on the purchase. That leaves no cushion for repairs after closing. According to Schipper, many buyers “just think they go shopping, and then they might be able to get pre-approved for a certain amount” without factoring in the full picture of what the home will actually cost to own and maintain. That pre-approval number doesn’t include property taxes, insurance (windstorm and flood), or renovation needs.
Insurance companies increasingly require updated roofs before issuing or renewing policies. Plumbing overhauls in older slab-foundation homes are disruptive and costly. Hurricane-rated windows carry a significant price tag per opening.
Budget Beyond Purchase
For buyers considering beachside Hollywood or Dania Beach homes, the practical consideration is straightforward: the purchase price is not the total investment. An inspection will reveal the scope of needed work, but by then a buyer has already spent time and money on due diligence. The smarter approach, according to Schipper, is to assume renovation costs from the start and shop at a price that leaves room for them.
Homes in the $400,000 to $800,000 range that are original but priced accordingly have been moving fastest in Schipper’s recent experience. Some have sold in one to two days. The buyers acquiring those homes appear to understand the trade-off: pay less upfront, budget for updates, and end up with a home whose total cost they actually control.
The million-dollar-plus homes that need the same level of work sit longer, partly because buyers at that price point expect polish they are not getting. Schipper notes that not everyone has $5 million for new construction on over an acre. That gap between what buyers can spend and what fully updated beachside homes cost explains why original, well-priced properties move faster.
About the Expert: Lilli Schipper is a Broker Associate with LoKation Real Estate who has worked in Broward County, Florida, for 22 years.
This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.
Similar Articles
Explore similar articles from Our Team of Experts.
So you’re moving to a new city, and the research has already begun. You can learn a metro’s prices, tax rates, and school ratings from a thousand miles away. What the research can’t show you is which neighborhood fits the life you’ll actually lead there. Helping you close that gap is now central to a ...
The Department of Veterans Affairs has narrowed the list of property conditions that can hold up a VA-backed purchase. Under an update to the VA’s Lender’s Handbook, appraisals ordered from May 1, 2026, no longer require repairs for peeling paint on homes built in 1978 or later, or for defects in detached sheds and garages. ...
When 60 to 70 percent of buyers in a market are spending accumulated real estate wealth rather than current earnings, the market operates by different rules than national economic indicators suggest. In Santa Barbara, that disconnect between price levels and income-based affordability is not a temporary distortion – it is the market’s defining feature, according ...
In most of Bucks County, Pennsylvania, the housing market runs on familiar suburban logic: limited inventory, competitive bidding, and first-time buyers stretching to qualify. In Pipersville, at the county’s northern edge, the math works differently. Farms outnumber listings, acreage is measured in dozens rather than fractions, and the buyers who show up are coming from ...
Prospective homebuyers waiting for mortgage rates to fall may be waiting for conditions that only a major global crisis would create. Current 30-year fixed mortgage rates of about 7.25% are not an anomaly, according to Jason Huerkamp of Huerkamp Home Group in the Twin Cities. That figure matches the historic 50-year average. The low rates ...