The American habit of trading up has stalled. For decades, owners moved to bigger homes as their families and paychecks grew; now millions are holding on to something the market no longer sells: a mortgage rate below 4%. Nearly half of all outstanding U.S. mortgages carried one in the second quarter of 2026, while a new 30-year fixed loan averaged 7.11%. For anyone who locked in between 2020 and 2022, moving now means trading that rate for one at least three points higher. For many, the math has already settled the question.
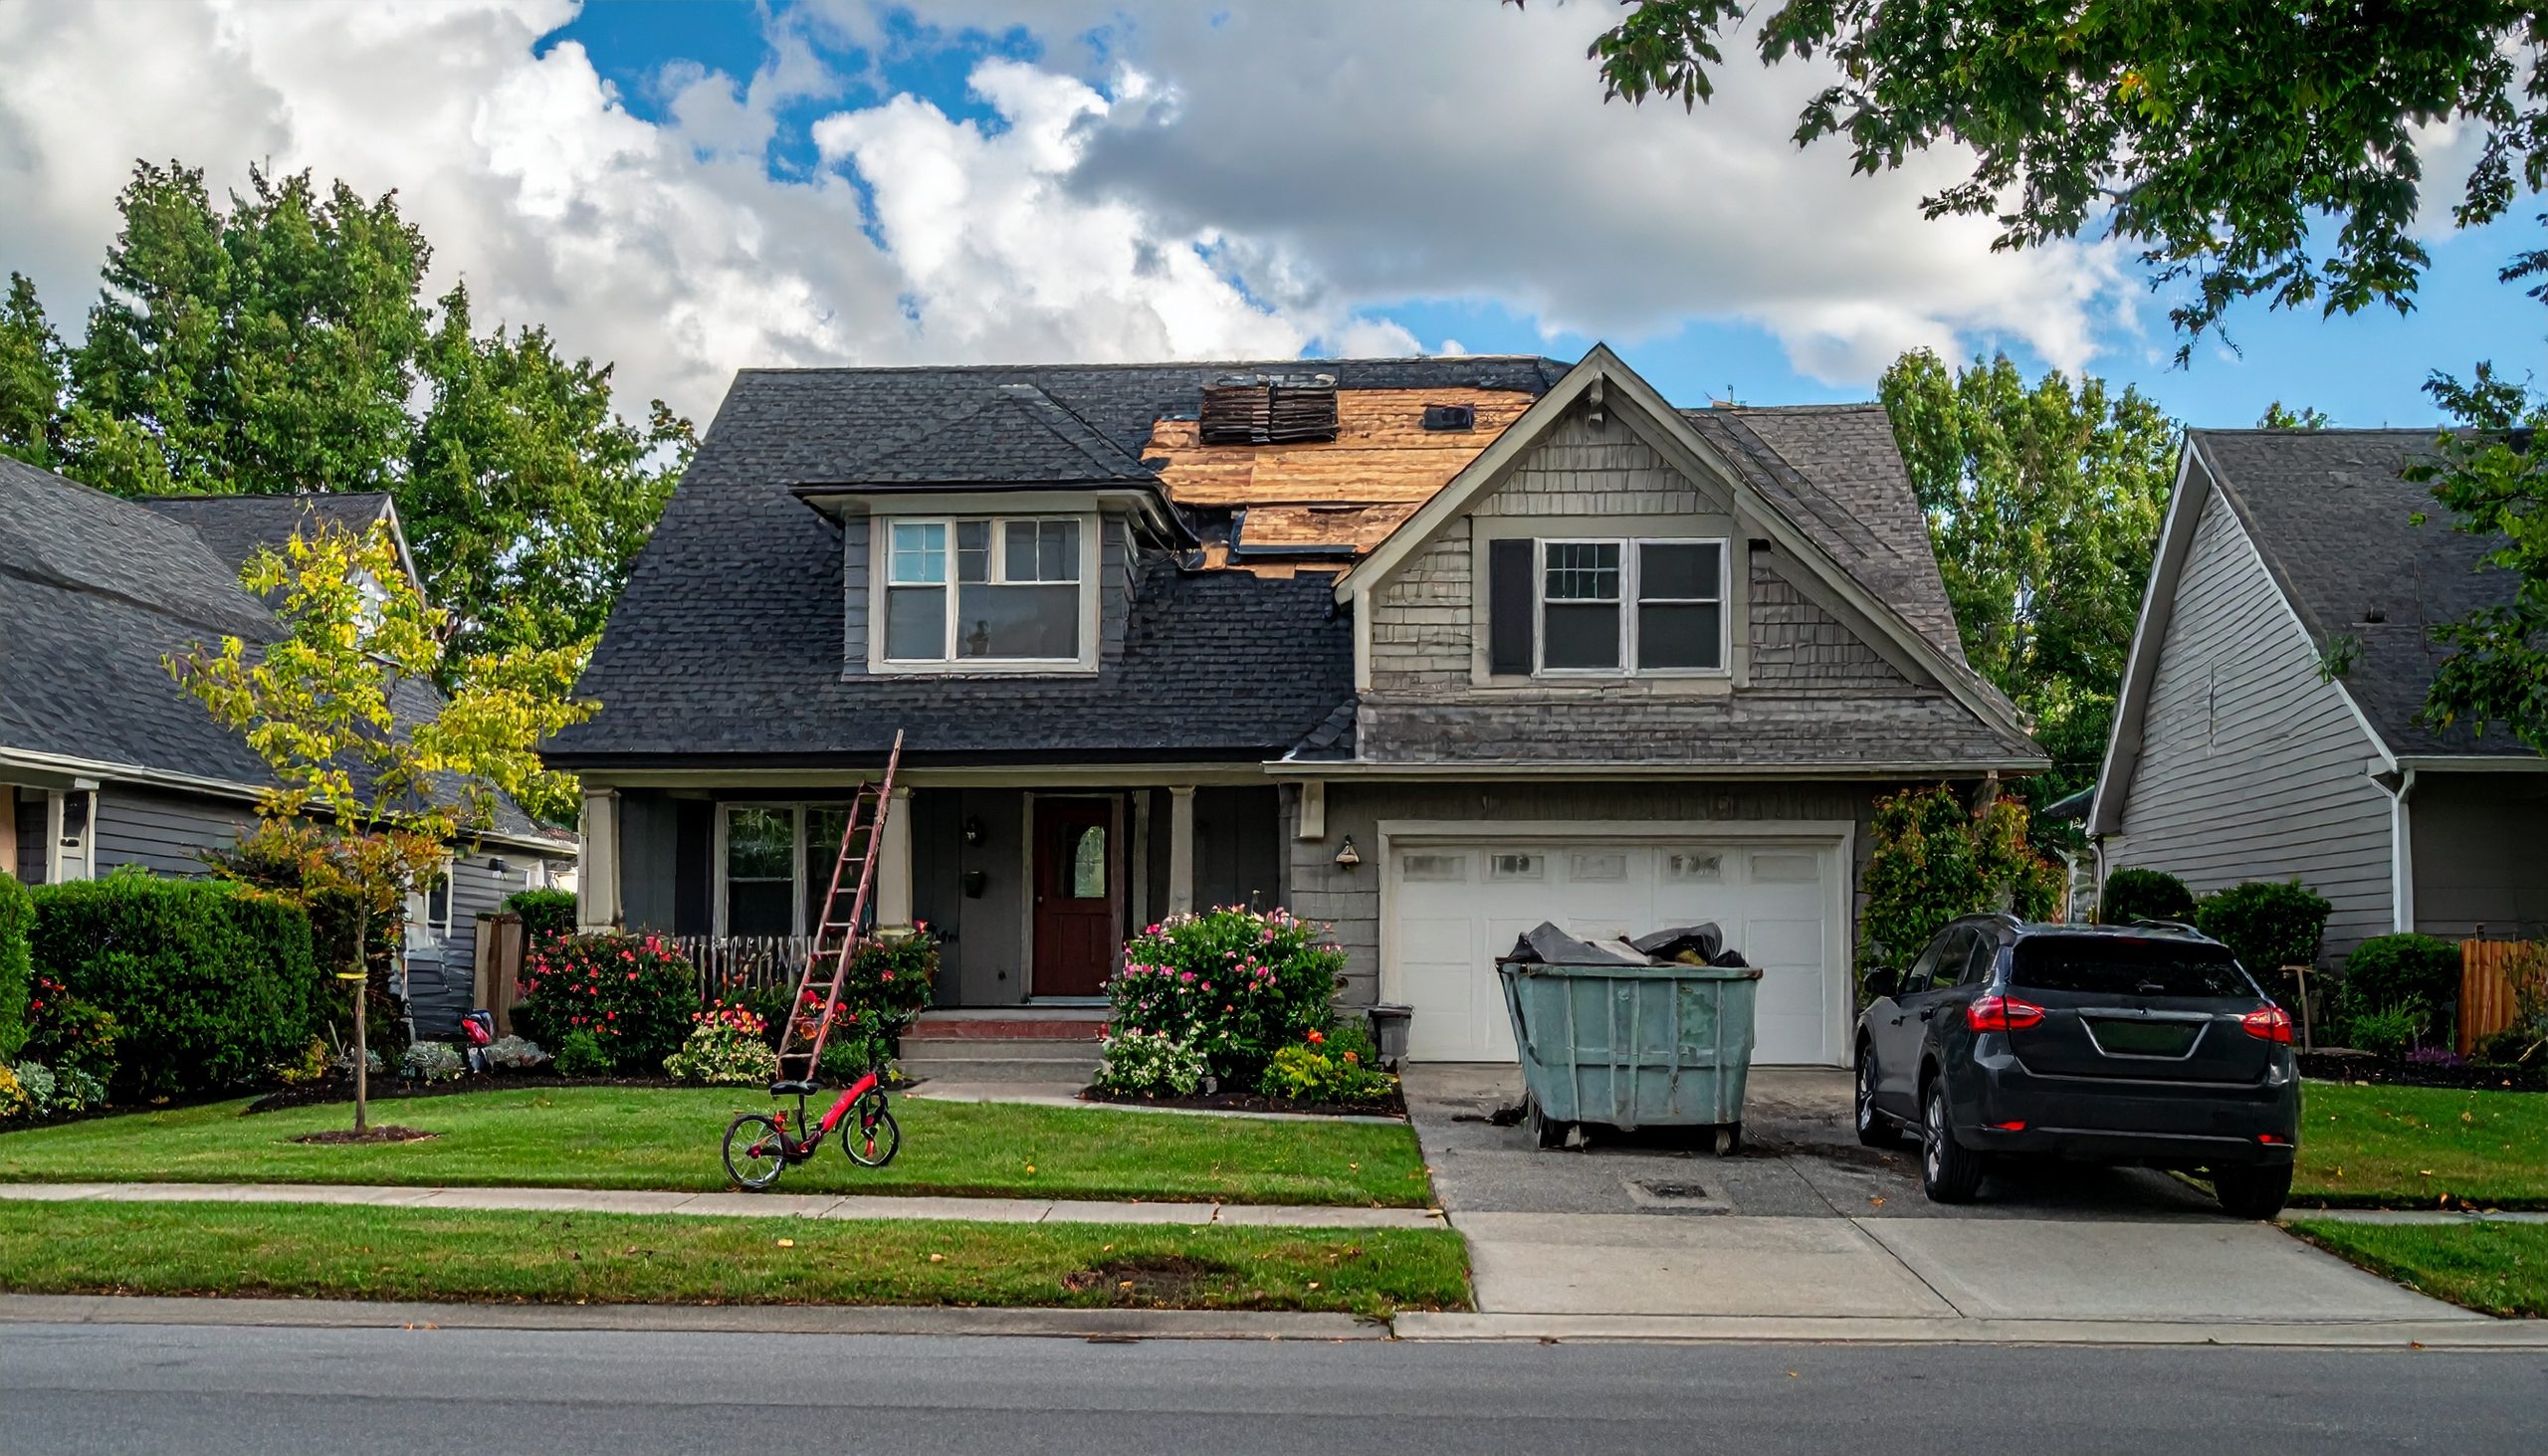
Staying put has not meant standing still. Owners who might once have moved up are putting money into the homes they already have, and more of them are borrowing against their equity to pay for it. This isn’t a remodeling boom; researchers expect national spending on home improvement to stay roughly flat. It’s a change in how Americans see the homes they already own.
Courtland Weisleder, president of DealerBridge.ai, a marketing company that works with private-equity-backed home service contractors, sees the pattern among the homeowners his company reaches. “People are wanting to upgrade their home because they’re going to be in there longer,” he says.
Saving Now or Selling Later
Weisleder describes two camps among homeowners investing in their properties. The first plans to stay for the foreseeable future and prioritizes upgrades that cut monthly costs: higher-efficiency air conditioning, attic insulation, tankless water heaters. “If I buy a new AC, is that going to reduce my electric bill? Yes, it should,” he says. He calls products that lower insurance and electricity costs “a no-brainer.”
The second camp plans to sell within a couple of years and focuses on kitchen and bathroom remodels. With fewer homes on the market but also fewer buyers at today’s rates, Weisleder says, sellers want their house to stand out from the rest of the neighborhood.
The Financing Squeeze
For homeowners who want to borrow, home equity is still among the cheapest money available. HELOC rates are near their highest level of the year, at around 7.5%, but that is roughly a third of what the average credit card charges.
Weisleder weighs a HELOC against what the same cash would earn sitting in Treasury bills, and argues the difference is worth paying for upgrades that cut monthly costs or add resale value.
That math has limits. Most HELOCs carry variable rates, so payments rise when the Fed raises rates; the loan is secured by the home; and the interest is tax-deductible only in specific cases. DealerBridge itself offers homeowners HELOC financing through a lending partner.
Climate and Energy Prices
What homeowners upgrade depends on where they live. Weisleder sees storm protection leading in the Southeast and insulation and heating systems in the Northeast: upgrades shaped by the local climate and the bills it drives.
Energy prices complicate the math. Californians pay roughly twice what Floridians do for electricity but use less than half as much, so the same upgrade can pay off very differently from one state to the next. “The climates are different, so it’s a balancing act,” Weisleder says.
Potential Headwinds
Several pressures could temper the trend. Weisleder points to diesel, which fuels the trucks that carry building materials; with prices well above last year’s, those costs filter into what homeowners pay.
Borrowing costs are unlikely to ease soon either. The Federal Reserve raised rates in September and is widely expected to raise them again in December, and because most HELOCs move with those decisions, payments on existing lines would rise too.
In addition, retail spending on building products has been flat to negative and remodeling permits have stalled, a sign of continued sluggish renovation activity.
Behind the Spending
The lock-in keeping owners in place is easing only slowly, and as long as it holds, improving the house will remain the default over moving.
What changes is which projects make sense. With borrowing costs high and likely rising, the strongest case belongs to upgrades that pay for themselves through lower bills or insurance premiums. For a country that used to trade up, the home is becoming something to invest in rather than move on from.
About the Expert: Courtland Weisleder is president of DealerBridge.ai in Jupiter, Florida, focusing on home services marketing and customer acquisition.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.