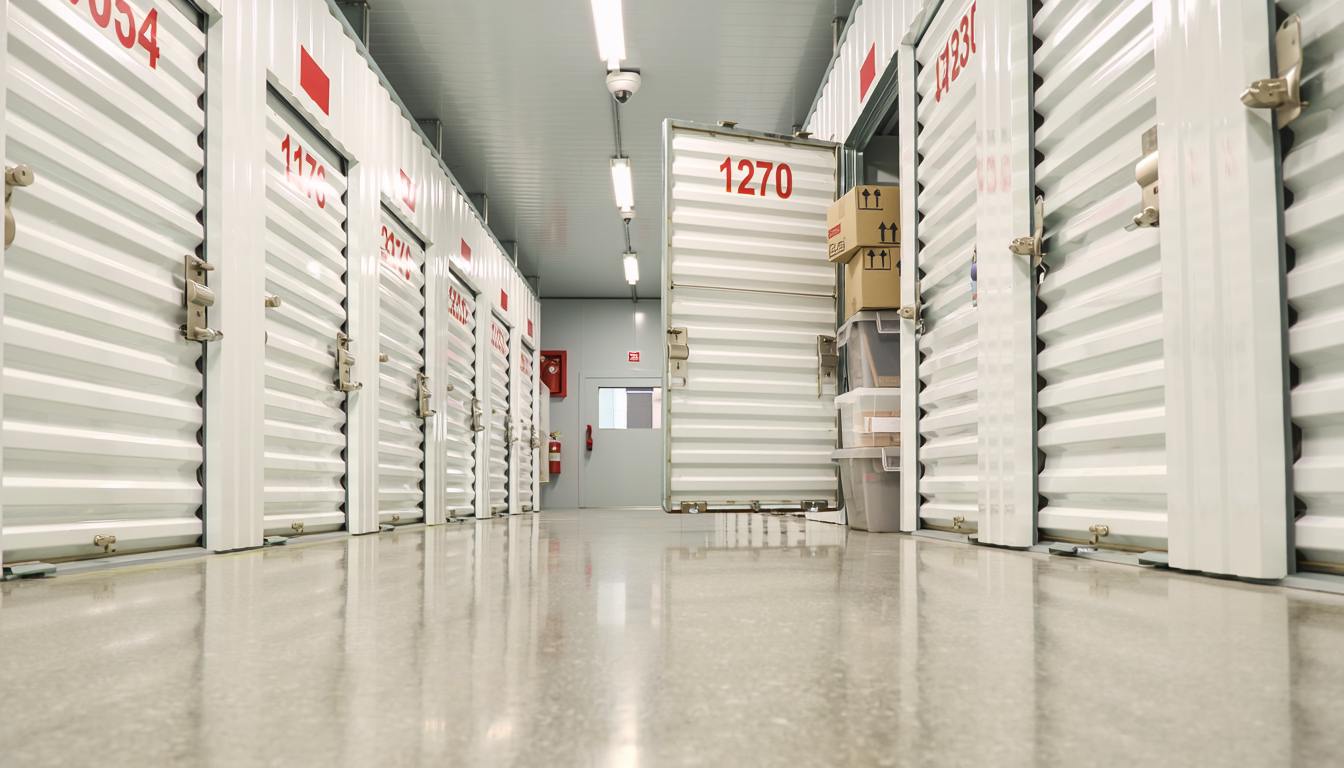
The pandemic-era self-storage construction boom created a distinctive opportunity in secondary and tertiary markets: a fresh supply of newer facilities whose performance depends closely on how well their scale aligns with the local population. According to Tom de Jong, Executive Vice President at Colliers, a pattern he has encountered repeatedly involves 100,000 square feet of rentable space built in trade areas with less than 50,000 people within a three-mile radius. Understanding how these facilities reach stabilized occupancy, and how their rent-growth potential compares with the larger markets developers used as their underwriting benchmarks, is central to evaluating them well.
What the COVID Boom Built and Where
De Jong’s observation comes from active deal flow: he has been representing buyers seeking newer Class A properties to minimize deferred maintenance considerations. In reviewing available inventory, a consistent pattern has emerged among recently built facilities in smaller markets.
“A lot of properties built in smaller markets are still working toward full occupancy after several years of lease-up,” de Jong says.
The dynamic, in de Jong’s view, is straightforward: developers underwrote these projects during a period when demand was so strong that market fundamentals in secondary locations appeared to mirror those in major metros. Occupancy was near 100% across the country, rent growth was strong, and tenant retention was high. Developers carried those conditions forward and sized facilities accordingly.
De Jong says those assumptions shifted as the market normalized. “They underwrote these during the boom times, when pretty much everything was full, and rates were great, and you could raise rents pretty much as much as you wanted, and nobody would leave,” he says. “And now in these smaller markets, it takes more care to fill at market rents. It takes more work to retain tenants, and rent increases need to be paced to the population base that supports them.”
The markets de Jong identifies as having received the most new construction during the boom years are Las Vegas, Miami, and a broad range of Texas and southern state markets, the same geographies that attracted the strongest development interest.
Understanding the Rent-Growth Dynamic
The key consideration for these assets is not only reaching stabilized occupancy, but what happens afterward. In a major metropolitan market, an operator who fills units through introductory pricing can then push rents upward because there is sufficient demand depth to absorb increases. Tenants who leave can be readily replaced. In a smaller market with a leaner population base, that pace calls for a more measured approach.
“In order to reach occupancy, you may start with attractive rates,” de Jong says. “And in a market with a smaller population, rent increases are best introduced at a pace the market can absorb.”
This creates a dynamic worth mapping carefully. Introductory pricing helps fill units, which sets in-place rents. When the operator moves to raise rents through existing customer rate increases, the size of the population base shapes how quickly turnover can be re-leased at higher rates. Reading that relationship accurately is where value is protected.
For buyers underwriting these assets, the classic self-storage value-add thesis (buy at below-market rents, move rates toward market, capture the spread) works best in a market that can absorb rent increases with manageable move-outs. In a smaller market, that thesis simply needs to be sized to local depth. The upside that looks compelling on paper is most reliable when it is matched to demographics.
De Jong notes that the analysis required to assess these situations is genuinely sophisticated. Determining achievable rent growth at a specific facility requires granular demographic analysis, competitive supply mapping, and a grounded assessment of the local population’s ability to pay market rates. “It’s very nuanced, and it takes a somewhat scientific approach to figuring out what you can achieve at a facility,” he says.
A Buyer Pool That Wants New Construction
The current oversupply of newer product intersects with strong buyer appetite for it. De Jong says the buyers he has been representing specifically want newer, Class A properties to minimize the capital expenditure considerations associated with older facilities. That preference is common in the current market: buyers who have watched maintenance costs affect returns on older assets are now willing to pay a premium for newer construction.
A meaningful share of available newer inventory sits in exactly the smaller markets where new development was most active. Buyers seeking new construction can pair that quality with a clear-eyed read of local rent-growth potential, an added layer of analysis that goes beyond a building inspection and rewards diligence.
The assets that perform best are newer facilities in larger markets with sufficient population density to support both lease-up and subsequent rent growth. Those assets are in shorter supply and command higher prices, so identifying the right opportunity across the full spectrum is where specialist advice pays off.
Matching Supply Scale to Market Depth
De Jong’s advisory practice involves helping buyers identify which newer assets are genuinely positioned for rent growth and how each one relates to the market around it. The due diligence process he describes goes beyond physical inspection. It includes detailed analysis of the trade area population, competitive supply, and the realistic rent trajectory given local demographics.
For developers and lenders active in self-storage construction, de Jong’s observations point to a clear and rewarding discipline: matching facility scale to the population base that will support it. A 100,000-square-foot facility may be well suited to a dense suburban market. In a market of less than 50,000 people within three miles, sizing is everything. De Jong says the current market offers a valuable lesson in aligning supply with demand, and a strong opportunity for buyers who bring that rigor to their acquisitions.
About Tom de Jong: Tom de Jong is Executive Vice President at Colliers and Founding Principal of the De Jong Self Storage Team. With 19 years at Colliers, a $2B+ transaction record across 32 states, and an SIOR designation, he is one of the most recognized specialists in self-storage brokerage and investment advisory in the United States. In 2026, the De Jong Self Storage Team launched a service dedicated to representing buyers.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.