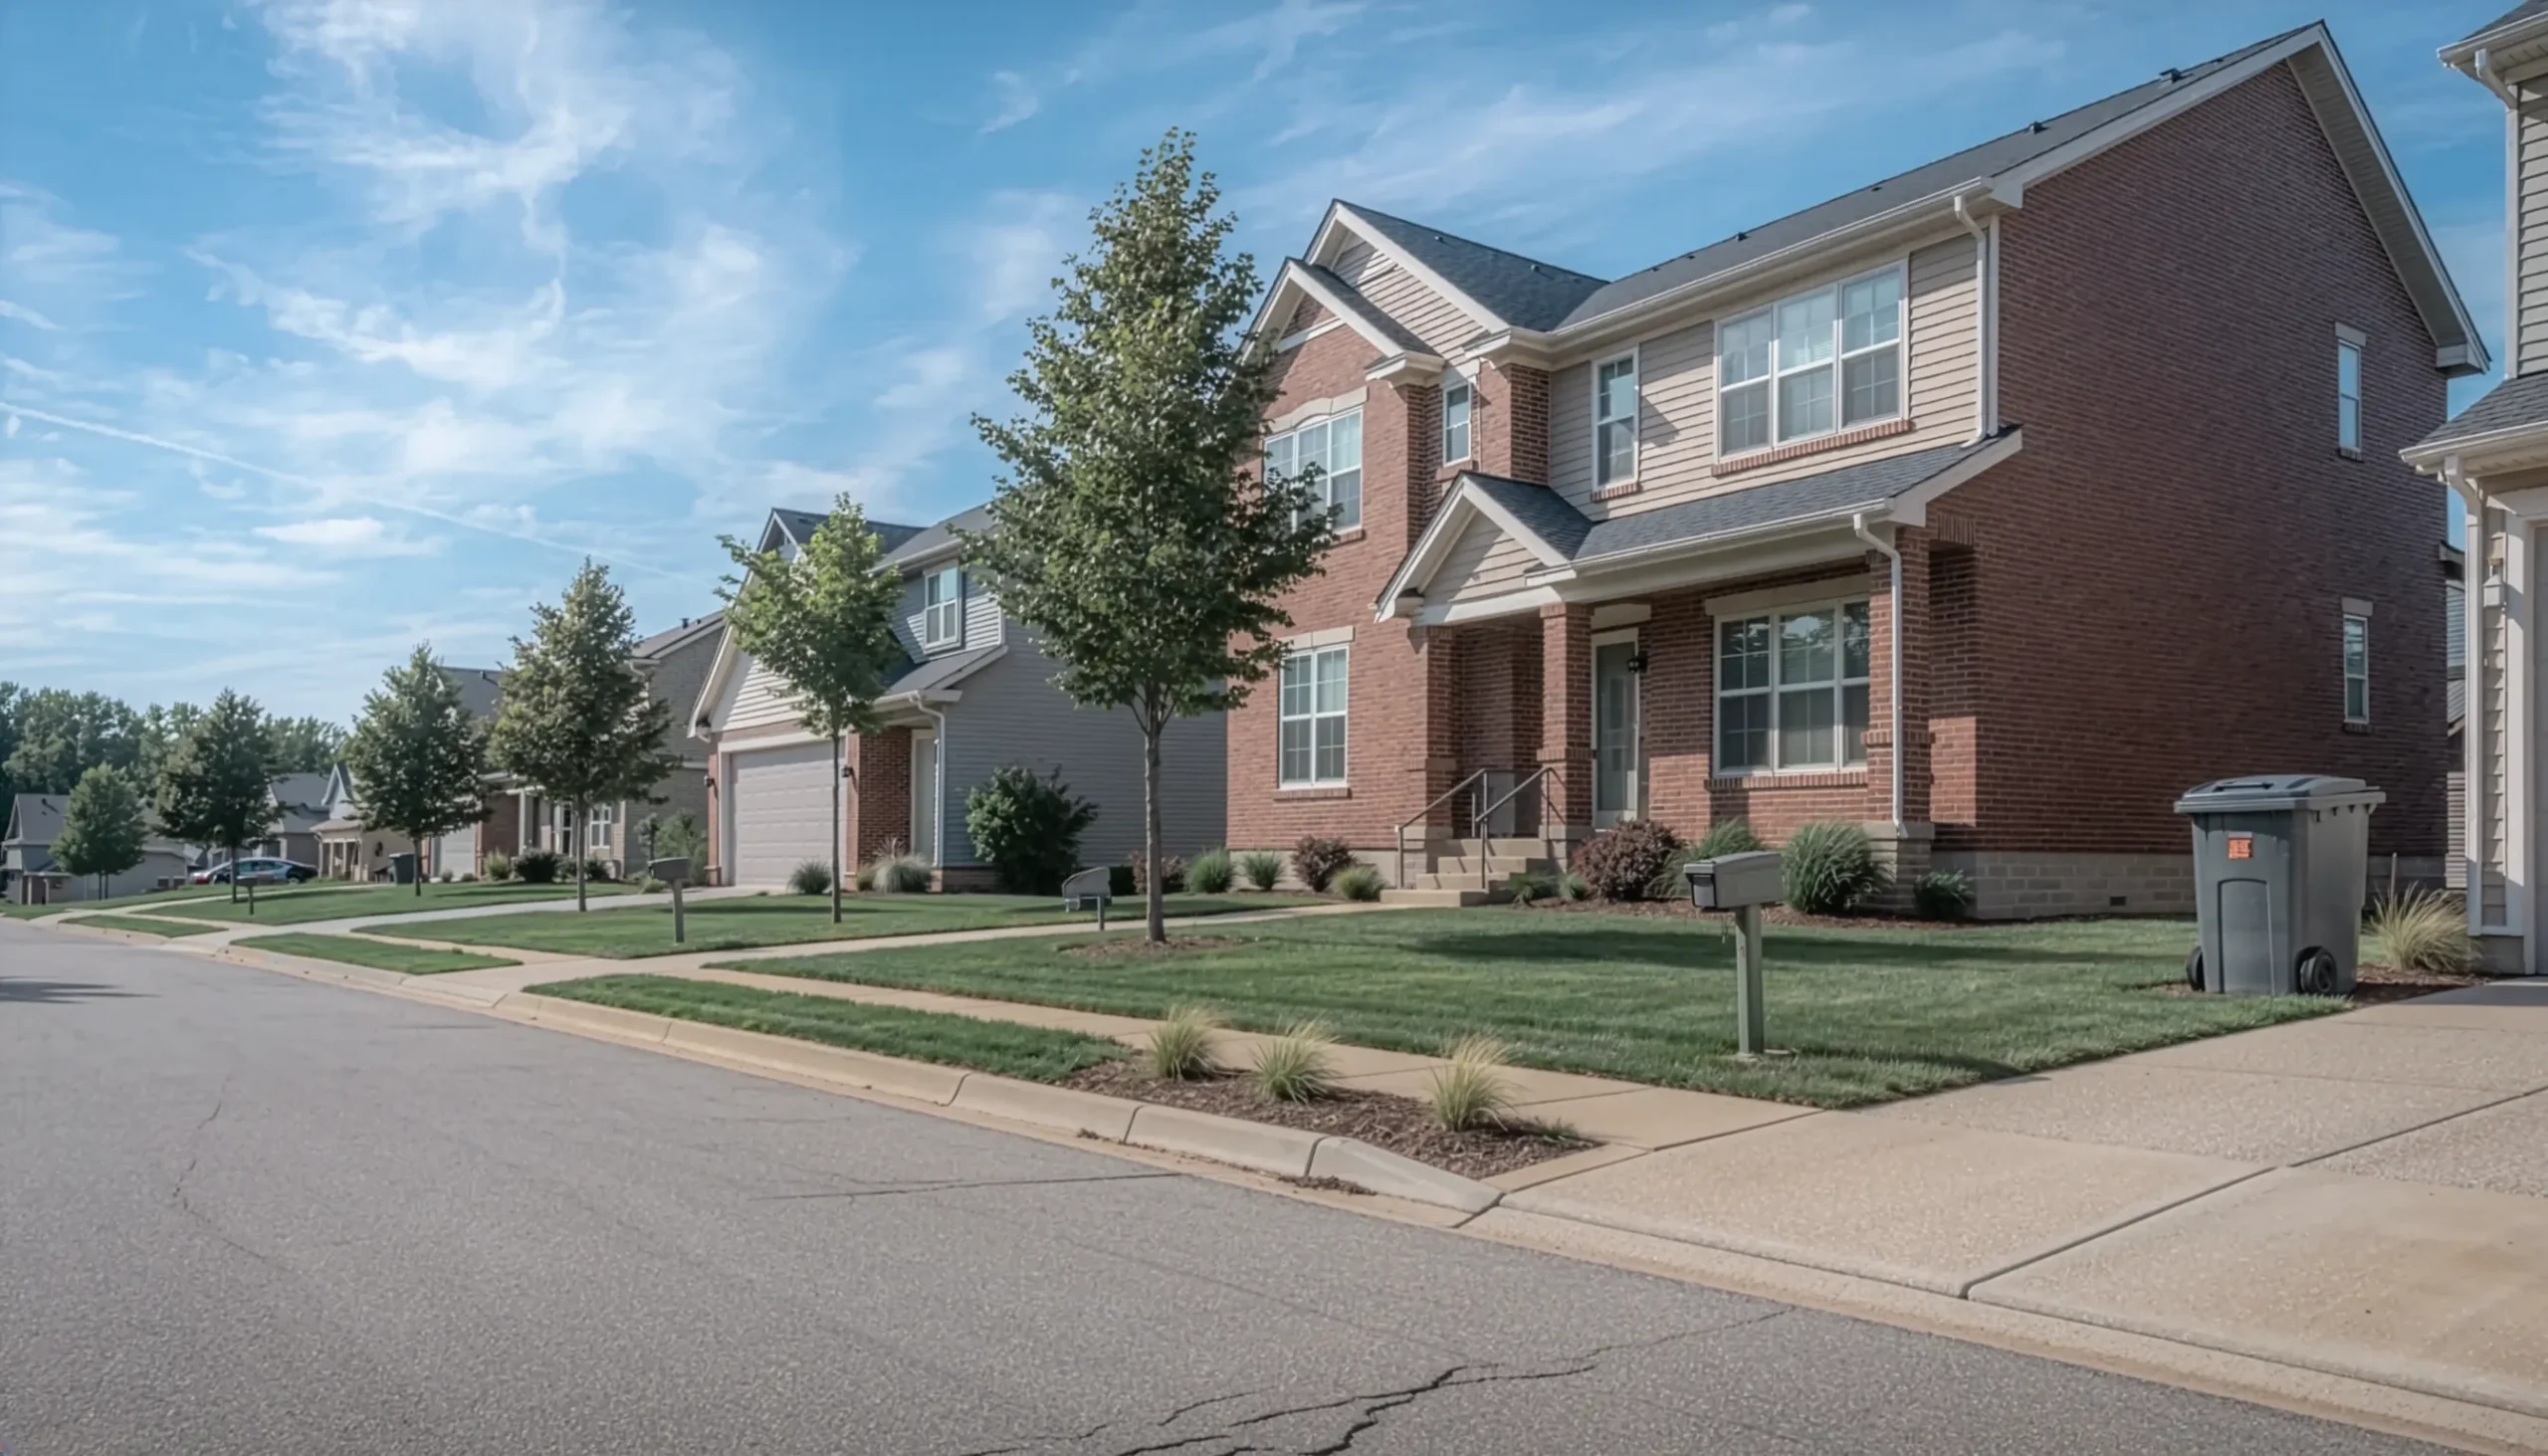
A home that doesn’t sell in its first three weeks on the Charlotte market now faces an average wait of roughly three months – a gap that reveals how sharply buyers are sorting properties into two categories. According to Jay White, who leads a 40-agent team in Charlotte and expects to close around 300 transactions this year, the best-priced, move-in-ready homes go under contract within a week or two, often at or near full price, sometimes with multiple offers. “If it doesn’t sell in those first 20, 21 days, then average days on market is more like 90, 95 days,” he says.
North Carolina led the country in population gain over the past year, and the Charlotte metro continues to attract corporate relocations, retirees, and growing families. But that demand is not lifting all listings equally. Buyers who are stretched on both down payments and monthly costs are passing over homes with deferred maintenance or soft pricing when comparable or better options exist for the same money.
New Construction Is Undercutting Resale
One of the forces widening that gap is builder competition. White says that in many cases it is now cheaper to buy new construction than resale in the Charlotte market – a reversal that puts direct pressure on existing homeowners trying to sell. Builders are offering significant incentives, particularly on townhomes, and buyers are responding.
White says buyers are drawn to new construction because they know they won’t face major repair costs in the first few years. That matters because many of these buyers are already at the edge of what they can afford. “They are stretching their budgets, both down payment in terms of the cost of the house and their monthly payment in terms of interest rate, to just get in the home in the first place,” he says.
For resale sellers, the math is unforgiving. “You can’t just have the best house, or you can’t just have the best price,” White says. “You have to have the best house at the best price to be able to win in this market.” Buyers who lose out on top-tier listings and eventually consider homes with deferred maintenance or weaker pricing are demanding serious concessions before they commit.
Who’s Moving to Charlotte
Charlotte is the second-largest banking center in the country behind New York City, and the financial sector continues to drive corporate relocations. White’s team recently published a breakdown of seven major financial firms that have moved headquarters or significant operations to Charlotte, including Bank of America, Wells Fargo, Truist, and SMBC, the third-largest bank in Japan. Those anchor employers attract a secondary layer of service providers – insurance, accounting, and related firms – that further expands the job base.
The buyer pool spans first-time purchasers, growing families, divorcing couples, retirees, and corporate transferees. White describes a recent example: a couple from Tulsa, Oklahoma, found his team through their YouTube channel, flew in to evaluate Charlotte as a retirement destination, and put an offer on a home in a 55-and-older community during their first visit.
Relocation buyers from expensive coastal markets tend to be struck by how much home their dollar buys. Buyers from smaller markets react differently. “It doesn’t feel like it’s as big as Atlanta or Houston, and it’s not,” White says. “But it has a lot of the amenities that those cities have.”
Growth is also pushing outward. Buyers seeking more space at lower cost are moving into the suburbs and across the South Carolina state line. York County draws families with the top three school districts in South Carolina, while Lancaster County is absorbing growth along the Highway 521 corridor as an extension of Ballantyne, one of Charlotte’s fastest-developing areas over the past two decades.
A Different Investor Profile
The investor landscape in the Charlotte metro has changed. The large institutional buyers active during the run-ups of 2012 through 2015 and again in 2020 and 2021 are far less present, according to White. His property management business now works primarily with small-portfolio owners – typically holding between one and five properties – and a growing number of what he calls “default landlords,” homeowners who cannot sell at a price they find acceptable and have opted to rent instead.
For investors looking to deploy capital, White points to the far suburbs, where rents have risen enough for the numbers to start working. First-time buyers, meanwhile, may find the strongest entry in new-construction townhomes, where builder incentives are most concentrated.
Interest Rates Remain the Determining Factor
Higher interest rates in the third and fourth quarter of 2026 have added inventory and extended timelines across the market. White notes that rates had begun to decline earlier in the year before geopolitical disruptions – conflict in Iraq and the ongoing war in Ukraine – pushed oil prices higher and drove up the cost of goods, reversing the trend.
“That’s the one thing that I think has the opportunity to heat the market up, but also cool the market off,” White says, “is those interest rates.”
For sellers, the implication is immediate. In a market where buyers can comparison-shop across a growing pool of listings – including incentive-heavy new construction – the homes that sell quickly are the ones that leave nothing to negotiate. Homes that don’t meet that standard face a wait measured not in weeks but in months.
About the Expert: Jay White leads the Jay White Team with Keller Williams Realty in Charlotte, North Carolina, covering the greater Charlotte metro and upstate South Carolina.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.