A retailer doing two million dollars a year on the mainland will not produce the same profit doing two million dollars in Hawaii. The revenue line looks identical. Everything beneath it behaves differently.
That gap is the single most common surprise for mainland operators evaluating their first Hawaii location, and it is entirely manageable once it is understood. The brands that have built successful flagships here did not find a shortcut. They modeled the market accurately before they signed.
Freight As A Line Item
The variable mainland operators least expect to matter is logistics.
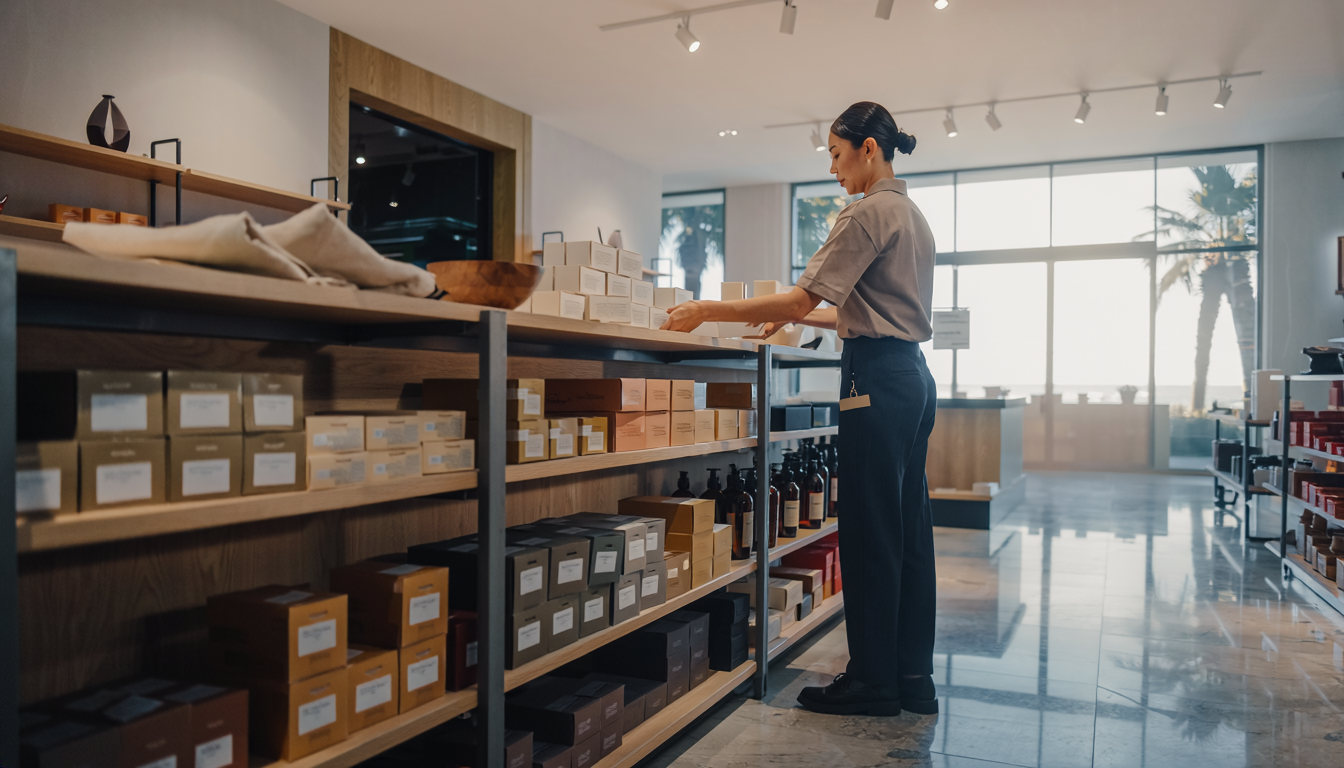
On the mainland, supply chain is largely solved. There are multiple carriers, competitive pricing, and short transit times. In Hawaii, every unit of inventory arrives by sea or air, carrying both a freight cost and a lead time that have to be planned around.
“It’s not a standard worry that they deal with on the mainland,” says Erin W.J. Mitsuyoshi, CCIM, of The Bratton Team at Colliers International Hawaii. The effect runs straight through to the operating statement, and it lands in a category operators do not always anticipate. Freight is not rent, but it consumes the same margin that rent does, which means it directly shapes what a tenant can afford to pay for space.
Recent trade policy has sharpened the point. Shifting tariff schedules have moved landed costs substantially on goods sourced through Asia, and the variability itself has been the harder part. Mitsuyoshi’s observation is that operators can plan around a known cost far more easily than around a fluctuating one. Where parameters are defined, a business can budget, forecast, and commit.
The Line Items Beneath
Several other costs run materially above mainland equivalents, and they compound.
Utilities are the clearest example, running at roughly double to triple the national average. Insurance has risen sharply. Hawaii also requires employers to provide healthcare coverage, which is a statutory obligation here rather than a discretionary benefit, and mainland operators frequently model it as the latter.
Rents sit above comparable mainland locations as well. None of these is hidden, and each is knowable before a lease is signed. What catches operators out is modeling two or three of them correctly and omitting the rest.
The Labor Market
Hawaii’s labor pool has been tight since the pandemic, and the practical consequence for operators is that wage floors are not the binding constraint.
The state minimum wage rose to sixteen dollars an hour on January 1, a two-dollar increase, with a further rise to eighteen dollars scheduled for 2028. Hawaii applies no tip credit, so tipped staff receive the full rate before tips.
For restaurant operators, Mitsuyoshi’s assessment is that this changes less than the headline suggests, because competitive employers already pay above minimum. In a market where experienced staff is scarce, compensation has been set by competition rather than by statute, and well-run operations have used bonus and tip pools to retain the people who perform.
The implication for a mainland operator is that labor should be budgeted at market rather than at minimum. The brands that recruit and retain well here treat that premium as a cost of operating in a tight market, and they get reliable staffing in return.
Where Occupancy Cost Lands
The number that brings all of this together is occupancy cost, expressed as a percentage of sales, and Hawaii sits above the mainland for a structural reason.
Standard retailers here generally run occupancy costs in the range of seven to twelve percent, depending on use and category. The comparable mainland band sits lower, commonly six to ten percent. Luxury goods and jewelry, with higher margins, can carry more. Grocery runs well below.
Everything described above feeds that gap. Rents are higher, and so are utilities, insurance, and the freight component embedded in getting goods to the islands. Each of those pushes the ratio up, which is why a Hawaii location carries a heavier occupancy load against the same sales volume than a mainland store would.
For landlords and operators alike, that is the key translation. A mainland rent-to-sales benchmark applied directly to a Hawaii location will understate what the position actually costs to hold. The ratio has to be adjusted for the cost structure underneath it, and assets across current Hawaii commercial inventory price accordingly.
Eyes Wide Open
None of this argues against the market, and the evidence on the ground makes that clear.
Hermès, Harry Winston, Tiffany and Louis Vuitton all operate successfully in Hawaii. They did not get there by finding cheaper utilities. They built models that accounted for the real cost structure and judged the position worth it, because a flagship address here carries weight on a global scale in the way that Rodeo Drive or the Champs-Élysées does.
The upside sits alongside the costs. Hawaii delivers strong retail sales, genuine customer loyalty, and a visitor base layered on top of resident demand. An operator with the right product and the right location can perform very well here, as a long list of retailers and restaurants demonstrates.
Mitsuyoshi’s summary is that the market rewards preparation. Go in with eyes wide open, plan for the time and the cost, and the numbers work. The operators who struggle are generally the ones who modeled Hawaii as a mainland market with better weather. Recently closed Hawaii transactions show how the market is pricing for operators who got that right.
About the Expert: Erin W.J. Mitsuyoshi (B), CCIM, is Associate Vice President with The Bratton Team at Colliers International Hawaii in Honolulu, specializing in retail leasing and landlord representation.
The Bratton Team is a Hawaii commercial real estate and investment sales group, exclusively contracted to Colliers International HI, LLC. Led by Mark D. Bratton (R) CCIM and Mike Perkins (S), the team has advised buyers and sellers across all Hawaii asset classes for 40 years.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.