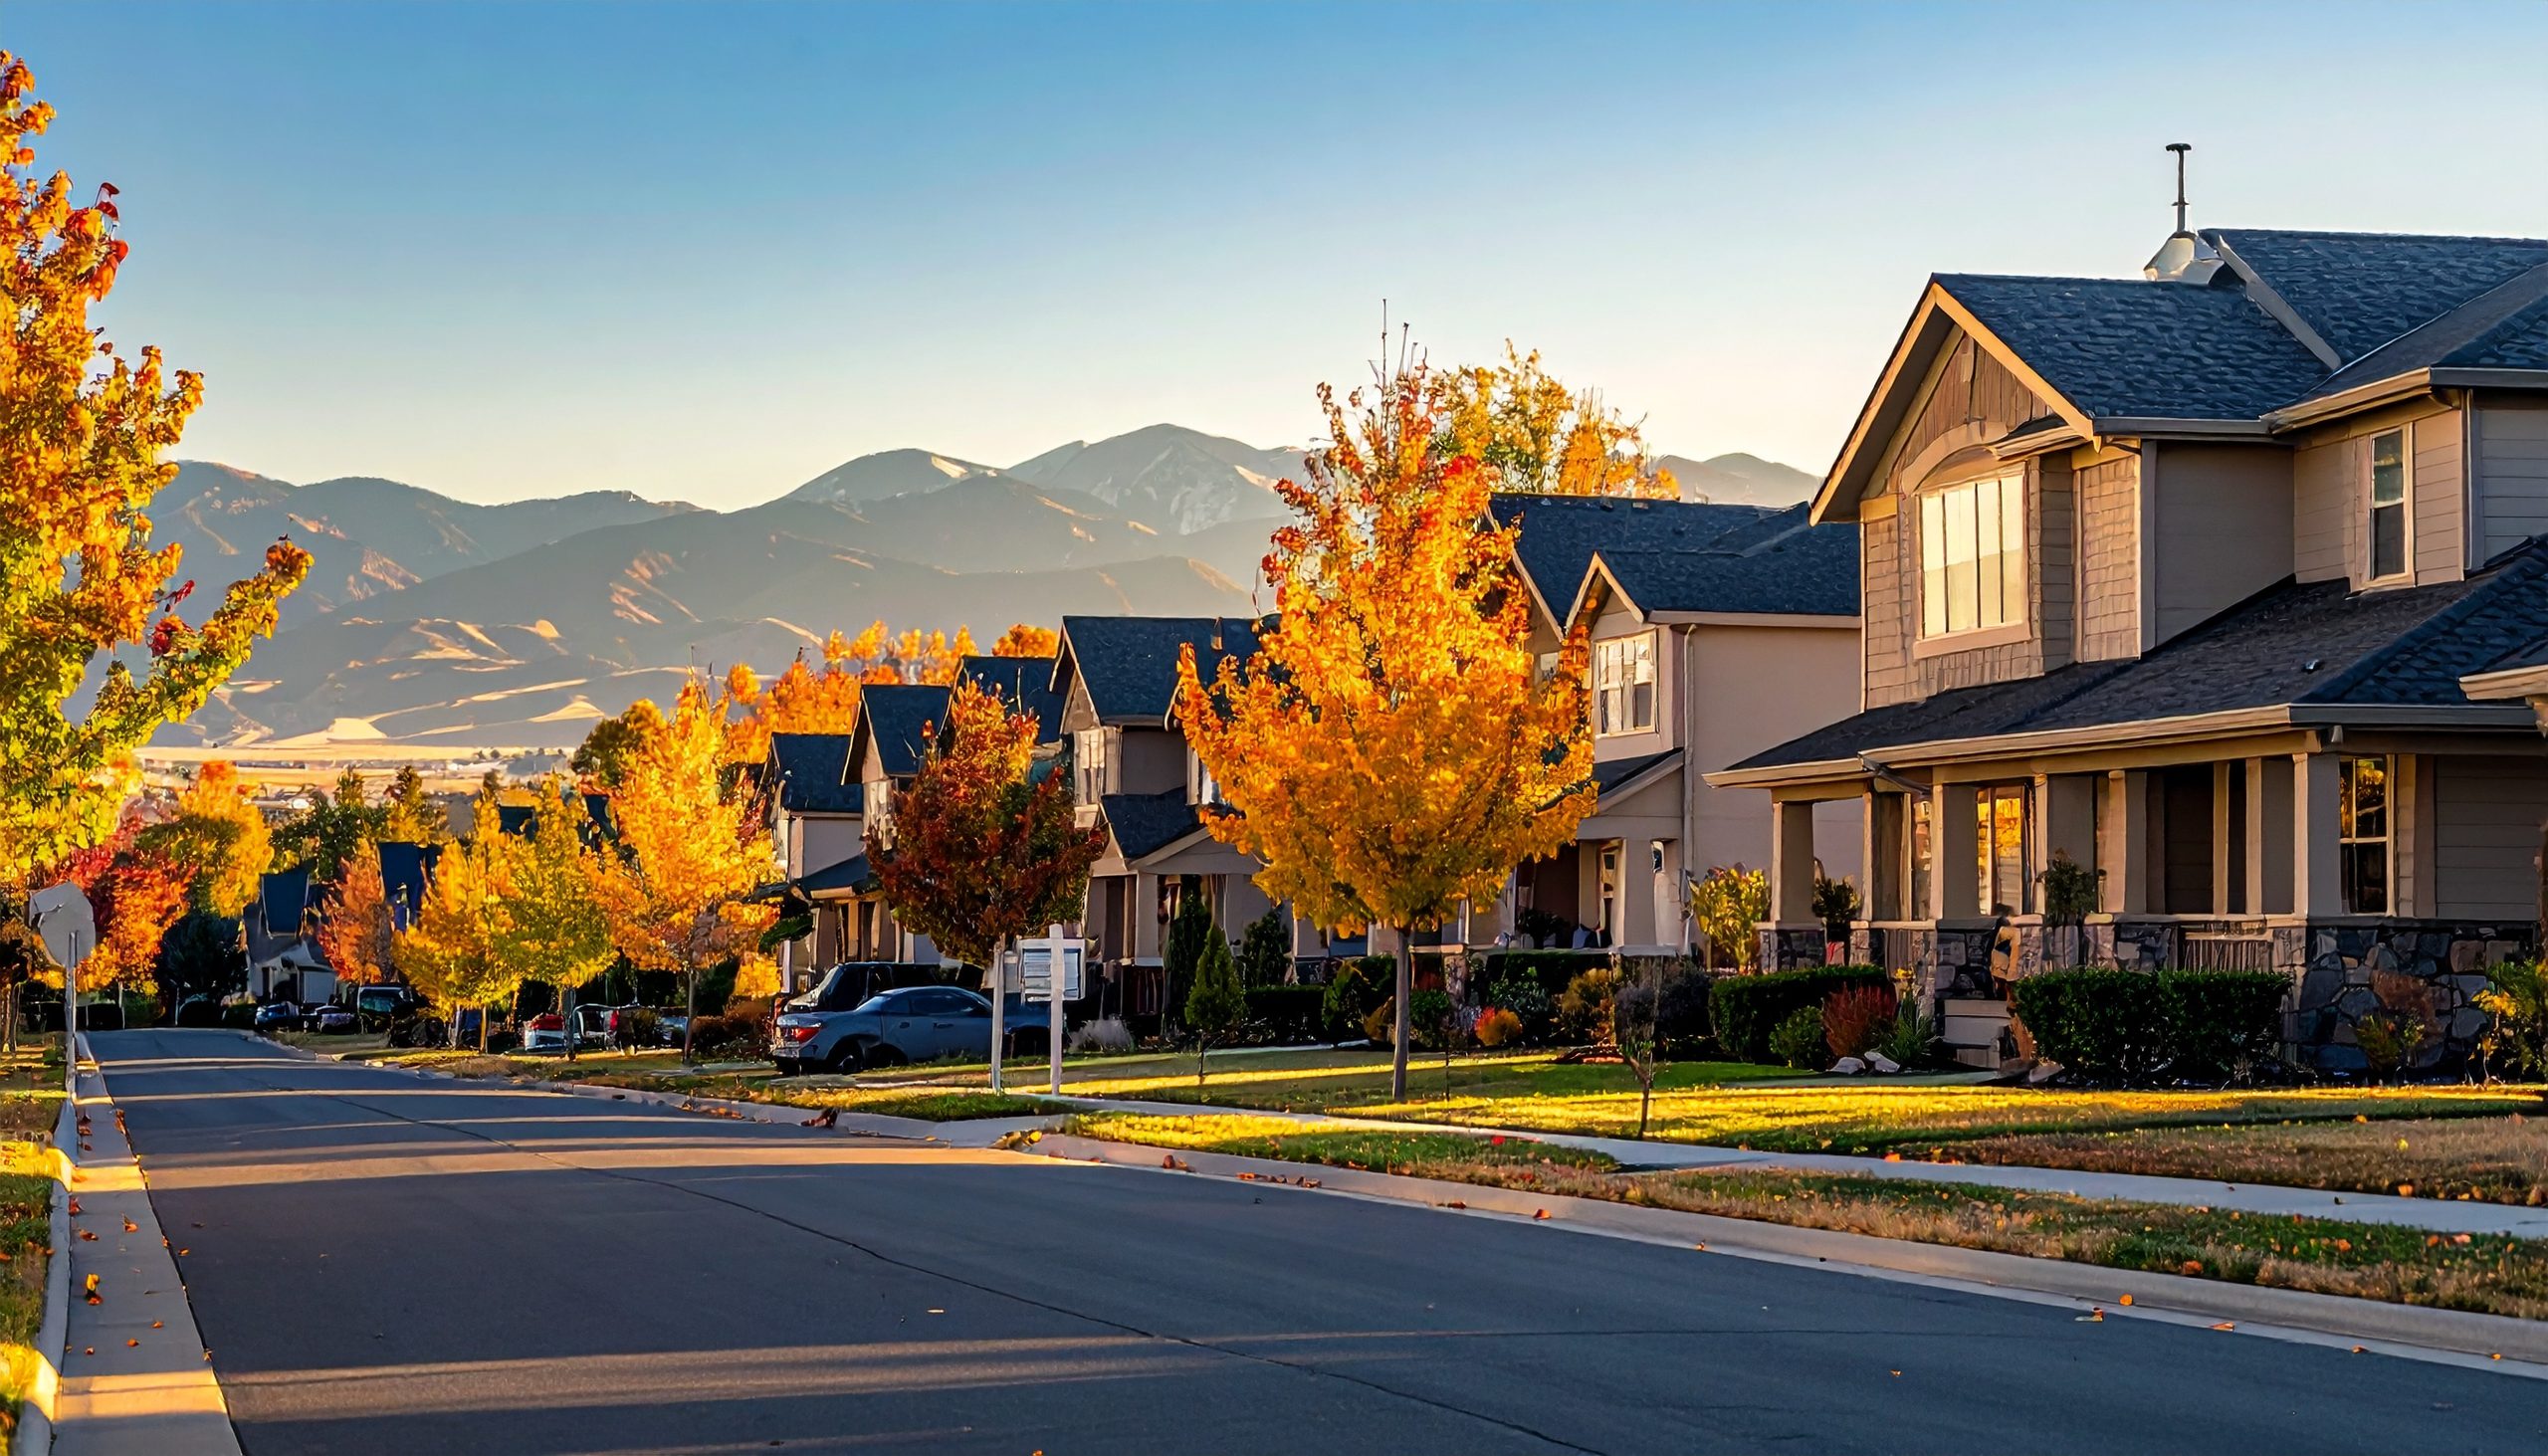
Across the country, more home sellers are cutting their asking prices than at any comparable point in recent years, as mortgage rates above 7 percent shrink the pool of buyers who can afford to purchase. Nowhere is that adjustment more visible than in Denver. In Redfin’s analysis of the 50 largest U.S. metros, the Denver area had the highest share of active listings with a price cut this September, at nearly one in three.
Landin Smith, who leads the Dream Smith Team in Highlands Ranch and has worked the Denver market for 19 years, says the cuts reflect a gap between what sellers remember and what buyers can pay today. “I think the false expectation is that Denver is always going to keep growing,” he says. “And it’s just going to grow and grow and grow.”
That expectation was built on a long run of appreciation. Now inventory sits at its highest September level in 15 years, closed sales have fallen sharply, and sellers in Denver’s south suburbs are learning that the asking price they start with shapes what they walk away with.
Pricing Low From the Start
For sellers, the most expensive decision is often the first one. A home listed at last year’s prices tends to sit, and every week on the market makes buyers more likely to wonder what is wrong with it. When the seller finally cuts the price, buyers sense leverage and negotiate harder.
Smith now advises his sellers to price 2 to 3 percent below recent comparable sales. In his team’s tracking, homes priced that way typically sell for close to full asking price within about two weeks. Homes that need even one price cut, he says, often end up selling for roughly 8 percent below their original list price, after weeks or months of carrying costs. Giving up a few points at the start, in his view, makes the whole sale “less painful.”
Metro-wide data shows the same pressure. Denver-area homes closed at about 98.5 percent of their final list price in September, according to the Denver Metro Association of Realtors. That figure counts the last price on the listing, so it hides the cuts many sellers made before reaching it.
Who Is Selling
With so many owners holding mortgages at rates far below today’s, the people listing now are mostly those who have to move. Smith calls it “a market for need, not for greed.” He sees growing families who need more space, workers relocating as employers call staff back to the office, and households changing careers as affordability pressure builds. Empty nesters downsizing remain part of the mix, but fewer than before.
That is part of why expectations lag. Many sellers bought or watched neighbors sell during years when Denver prices only climbed. Single-family values have since held roughly flat, Smith says, while condos and townhomes have slipped. DMAR’s September report shows the same split: attached homes carry the most inventory in the metro, and their median price has fallen year over year.
Competing With Builders
Resale sellers face the toughest competition in the parts of the metro still being built out. Close-in areas are largely developed, so new construction has pushed to the edges: Aurora and Parker to the east, Castle Rock to the south, and Thornton, Broomfield, and Brighton to the north. Builders there can offer low fixed mortgage rates that an individual seller cannot match.
Smith points to Sterling Ranch, a large master-planned community in Littleton, as an example. Owners who bought there a few years ago and now need to move for work or family find themselves listing next to brand-new homes with financing incentives attached. Unless those sellers compete hard on price, Smith says, “you may be there for a while.”
For these sellers, an aggressive starting price matters even more. A buyer comparing a resale home to a new one is often comparing monthly payments, not just sticker prices.
Where Buyers Are Showing Up
Demand has not disappeared; it has narrowed. Cash buyers, whom Smith estimates make up about a fifth of his market, are largely unaffected by rates. Many are downsizers who sold a high-end home and are buying their next one outright. DMAR’s data points to the same conclusion: sales of homes priced at $1 million or more are up this year even as overall closings decline.
Jobs are another source. Lockheed Martin plans to expand its space operations in the south and west suburbs over the next few years, hiring engineers, technicians, and support staff, with part of that growth in Douglas County, home to Highlands Ranch. New hires relocating for well-paid jobs are the kind of buyers who can still qualify at today’s rates, and Smith expects them to feed local housing demand.
Public school employees also have a new option. A state program launched this summer helps them cover a large share of their down payment and closing costs through a second loan, repaid along with a portion of the home’s appreciation when they sell or refinance. “It’s like bringing things back to pre-pandemic pricing for teachers so that they can afford homes,” Smith says.
What Sellers Can Take From It
Rates eased slightly in late October but remain above 7 percent, and DMAR expects softer closings through the end of the year as the September rate climb works through the pipeline. In that environment, waiting for the market to come back to a seller’s number is a strategy with real costs.
Smith’s advice is to start from where buyers are, not where prices were. For homeowners in Denver’s south suburbs, especially those competing with new construction, the first price is likely to be the most important decision of the sale.
About the Expert: Landin Smith leads the Dream Smith Team, a seven-agent residential team based in Highlands Ranch, Colorado. He has worked in the Denver real estate market for 19 years, focusing on listing preparation and buyer representation in the south suburbs.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.