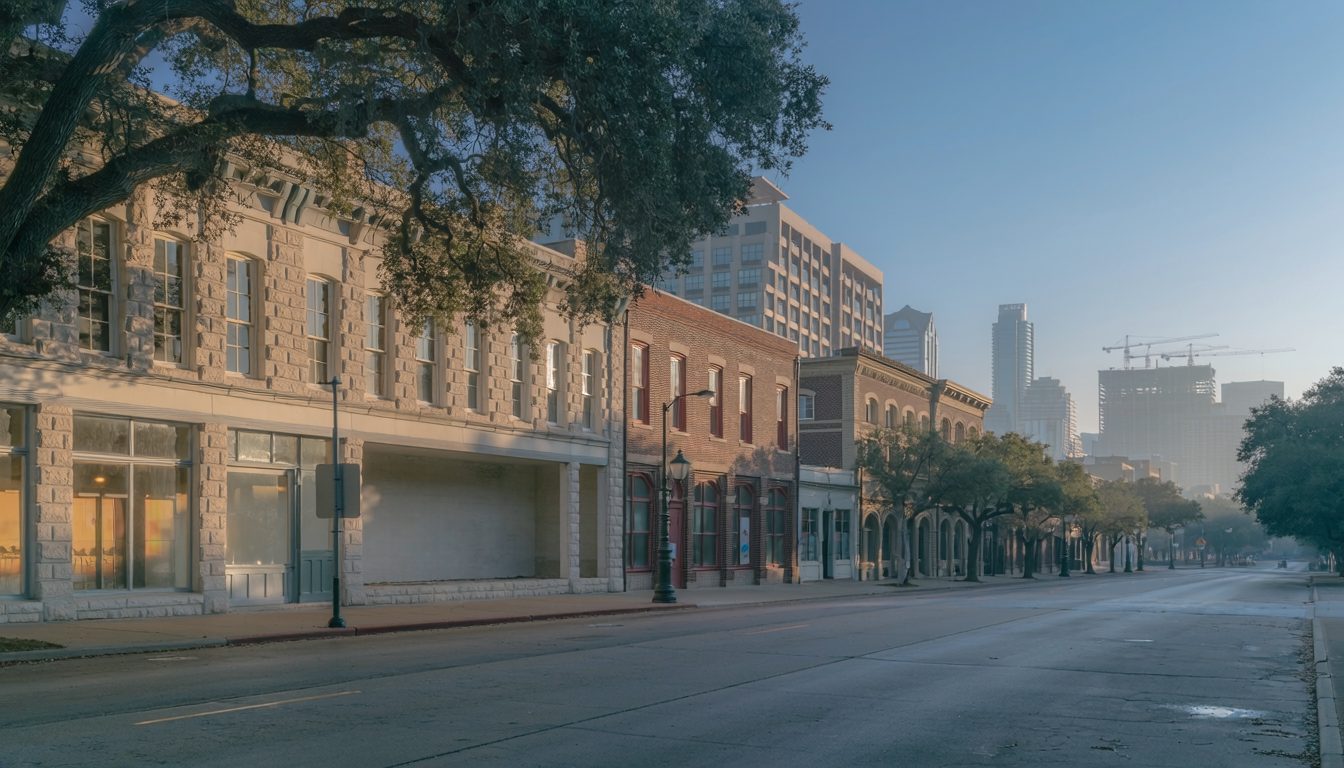
Austin’s commercial real estate market is often discussed as a single entity – hot or cold, booming or correcting. In the private market, where business owners and smaller investors buy individual buildings, the picture is more fragmented. Retail space is scarce, and landlords hold the leverage. Office and industrial buildings have more empty space, giving tenants and buyers room to negotiate. Apartment values, meanwhile, have reset downward after a wave of new construction.
Greg Cooper, a commercial broker who works in the $1 million to $10 million private market in Austin, sees the split reflected in who is buying. In his practice, investors have pulled back, while owner-occupiers – business owners buying or leasing space for their own operations – remain active.
Four Markets, Four Realities
The divergence across Austin’s commercial sectors is sharp enough that a buyer’s experience depends largely on the type of space they need.
Retail is the tightest category. Space is scarce, landlords hold the leverage, and Cooper says owners of performing buildings have little reason to sell.
Industrial is the opposite. A rapid building cycle tied to the region’s manufacturing growth left more space than tenants have filled, which gives buyers and tenants room to negotiate.
Office is in a similar position, still working through the drop in demand that followed the pandemic, though Cooper says it is beginning to rebound.
Multifamily is the most challenged. A wave of new apartments outpaced demand, values have fallen, and Cooper describes a standoff between sellers and buyers who cannot agree on price.
For anyone evaluating Austin commercial real estate as a single market, the contrast between scarce retail space and plentiful office space shows how much sector-level conditions shape the terms of a deal.
The Shift Toward Owner-Occupiers
With investors cautious, Cooper says more of the activity in Austin’s private commercial market now comes from business owners looking to house their own operations. Many of these businesses were started in the years since the pandemic, part of a broader wave of entrepreneurship, and Cooper says service businesses such as gyms, wellness centers and medical practices are generating enough cash flow to take on real estate.
Whether those owners buy or lease depends mostly on where the business is headed. A stable practice with no plans to grow can build equity by owning its building.
A company expanding quickly, especially into other cities, is often better off leasing. A lease keeps it free to move, and landlords typically help pay to build out the space, a cost an owner would have to finance alone.
Either way, the decision follows the needs of the business rather than market timing, which is what Cooper sees separating today’s owner-occupier activity from the investor-driven deals of recent years.
Total Cost of Ownership
Interest rates have complicated the buying calculus, but Cooper argues the full picture requires looking at total cost of ownership rather than rates alone. Higher rates raise the cost of borrowing, but they have also pushed some property prices down. A buyer paying a higher rate on a lower purchase price can end up with a monthly payment close to what the same business would pay in rent.
When that happens, Cooper says, buying can still make sense, because the owner builds equity with payments it would otherwise make to a landlord.
That logic depends on the sector. Apartment and office prices have come down from their highs, so the trade-off can work there. Retail and industrial prices have kept rising, so buyers in those sectors face higher borrowing costs without the cushion of a lower price.
For business owners weighing the decision, a side-by-side comparison of total ownership cost against current lease rates on equivalent space says more than the interest rate alone.
Keeping Investors on the Sideline
The investment side of Austin’s market has cooled for reasons that extend beyond interest rates. Cooper says broader economic and political uncertainty has led many investors to wait before committing capital.
“I’ve had quite a few people sort of pause, and they’re just waiting to see how things shake out,” he says.
Owner-occupiers, by contrast, are buying or leasing because their businesses need the space, not because of the returns they expect, and that has kept them active.
That shift matters for anyone reading Austin’s market. Slower investment sales do not necessarily mean the market is weakening – they may simply mean a different kind of buyer is doing the deals.
About the Expert: Greg Cooper is a commercial broker with the Cooper Advantage Group at Kuper Sotheby’s International Realty in Austin, Texas, focusing on private-market commercial real estate.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.